Scott Nyquist discusses why hydrogen may be down, but not out. Photo via UH.edu

Not long ago, hydrogen was hailed as the next big thing in clean energy. Investors poured in, and countries from Japan to Germany built ambitious hydrogen strategies. It wasn’t a new discovery; hydrogen has been used for over a century in refineries and fertilizers, but it suddenly found itself reborn as the world began working toward decarbonization.

When hydrogen burns, the only byproduct is water. Green hydrogen, produced with renewable power, could replace fossil fuels in everything from trucks to ships to steel mills. But the momentum has cooled. Costs remain stubbornly high, several projects have been delayed or canceled, and policy support has wavered. In the U.S., a change in administration has created uncertainty. In Europe, some governments are slowing funding or revising hydrogen mandates. Even the International Maritime Organization (IMO) recently postponed a key vote on fuel-carbon standards.

Yet as Mike Graff , former Chairman and CEO of American Air Liquide, said in an Energy Forum episode with Ed Emmett at Rice University’s Baker Institute, “The world is always looking to make sure that energy is first available, it’s affordable, and then it’s clean. And I see hydrogen over time evolving in that manner.” He also noted that “companies have produced hydrogen and utilized hydrogen for over 100 years, and they’ve done that very safely… I think we can continue that moving forward.”

China has doubled down on hydrogen as part of its industrial strategy, building massive electrolyzer manufacturing capacity and funding dozens of pilot projects across transportation and heavy industry. Japan and South Korea also stand out as examples of how sustained policy support can drive hydrogen progress.

Where Hydrogen Fits Today

To understand hydrogen’s role now, it helps to remember what it actually does. About 76 percent of global hydrogen is produced from natural gas and used in refineries, fertilizer plants, and chemical production. This so-called “gray hydrogen” is essential but carbon-intensive.

What’s new is the rise of low-carbon hydrogen, “blue” hydrogen made from natural gas with carbon capture, and “green” hydrogen produced by splitting water with renewable electricity. These methods are expensive, but they’re growing. According to the International Energy Agency, global low-emissions hydrogen output rose about 10 percent in 2024.

Hydrogen is also expanding beyond industry. As Graff explained, it already powers thousands of forklifts in warehouses across the U.S. and is beginning to appear in commercial trucking, locomotives, and even aviation prototypes. “You can now drive 600 to 800 miles on a hydrogen fuel-cell truck,” he noted, “and refuel in 30 minutes, just like you would refill for diesel.”

The Cost Challenge and a Gulf Coast Opportunity

So why the slowdown? One word: economics.

Even with generous tax credits, green hydrogen can cost two to three times more than conventional fuels. Electrolyzers are still expensive, though costs are falling as Chinese suppliers introduce low-cost alternatives.

Infrastructure is another hurdle. Pipelines, storage, and fueling networks need to be built from scratch.

But those same challenges point to opportunity, especially along the U.S. Gulf Coast. The region already has one of the world’s largest hydrogen pipeline systems and a well-established energy infrastructure. Texas, in particular, has a head start. It already hosts nearly 1,000 miles of hydrogen pipelines, about 64 percent of the U.S. total, and some of the world’s largest hydrogen storage sites at Moss Bluff, Spindletop, and Clemens. Out of 140 hydrogen plants operating nationwide, 43 are in Texas, supported by extensive refining and natural gas infrastructure. This combination of assets gives the Gulf Coast an unmatched foundation to scale low-carbon hydrogen and integrate production, storage, and end use across industries.

As Ken Medlock , Senior Director of the Center for Energy Studies at Rice University’s Baker Institute, explains in his report: Developing a Robust Hydrogen Market in Texas, Texas has all the critical elements needed to lead in a low-carbon hydrogen economy, including existing infrastructure, a skilled workforce, and proximity to industrial demand centers. That combination gives it a distinct advantage in scaling up hydrogen production and use.

Governments around the world are showing renewed confidence in hydrogen. The European Commission awarded nearly €3 billion to 13 major projects, while Japan and South Korea continue expanding fueling networks. China is leading one of the most ambitious buildouts, with more than 50 planned hydrogen projects and a rapidly growing fleet of fuel-cell vehicles. Despite recent setbacks, global investment has surpassed $100 billion, and projects in places such as Chile, where strong renewables and low-cost Chinese equipment help make projects feasible, are moving toward final investment decisions.

What Comes Next

Hydrogen’s future won’t depend on replacing every fuel, but on filling the gaps where batteries and biofuels fall short.

Transportation: This is where momentum is strongest today. Batteries dominate cars, but hydrogen fuel cells excel in heavy trucks, ships, and planes. As Graff noted, “You can design a commercial vehicle with the same utility as diesel but powered by hydrogen.” Airbus and Boeing are testing hydrogen propulsion concepts, and several ports are experimenting with hydrogen bunkering for cargo ships.

Industry: Steel, cement, and chemicals account for a quarter of global emissions. Hydrogen-based direct-reduced-iron (DRI) steelmaking is being piloted in Europe and Asia and could transform how these materials are produced at scale.

Storage: Hydrogen can store energy for days or weeks, serving as backup for renewables like wind and solar. But storage remains very costly and may only prove viable for the “last mile” of greenhouse gas reduction or grid stability.

These uses may sound niche, but that’s how technologies scale. They start small, gain an economic foothold, and expand as costs decline.

Conclusion

Hydrogen's early, perhaps irrational, exuberance may have cooled, but amidst the rubble of cancelled projects are the beginnings of an industry that could play a vital niche role on the journey towards a lower carbon intensity energy future. As costs fall and infrastructure around the world expands, hydrogen's role will expand into the nooks and crannies of the energy industry.

It won't replace every fuel, but it doesn't have to. Success will come from steady, project-by-project progress.

-----------

Scott Nyquist is a senior advisor at McKinsey & Company and vice chairman, Houston Energy Transition Initiative of the Greater Houston Partnership. The views expressed herein are Nyquist's own and not those of McKinsey & Company or of the Greater Houston Partnership. This article originally appeared on LinkedIn.
Scotty Nyquist discuss the growth in AI data centers and the strain on the system. Photo via HARC report

Houston energy expert asks: Who pays when AI outruns the power grid?

Guets Column

For most of the past 20 years, U.S. electricity policy relied on predictable trends in demand. Electricity use, in most regions, increased gradually, forecasts were stable, and utilities adjusted the system in small steps. Power plants, transmission lines, and substations were generally added to reflect shifts in load, rather than growth, and costs were recovered through modest adjustments to customer bills.

Growth in AI data centers has disrupted this model. A single facility can add as much electricity demand as a small town. That demand comes all at once, runs continuously, and has little tolerance for outages. If electricity service drops even briefly, computation stops, and services shut down. Ironically, data centers need reliable service, a point that their emergence is driving concern around for the rest of the grid.

What the numbers say

The International Energy Agency projects global electricity consumption from data centers to double by 2030, reaching roughly 945 TWh, nearly 3 percent of global electricity demand, with consumption growing about 15 percent per year this decade. McKinsey projects that U.S. data center demand alone could grow 20–25 percent per year, with global capacity demand more than tripling by 2030.

After years of roughly 0.5 percent annual demand growth, many forecasts now place total U.S. electricity demand growth closer to 2–3 percent per year through the mid-2030s, with much higher growth in specific regions. In Texas, some forecasters are saying electricity demand could double over the next five years, a staggering 10 percent per year growth rate. What sounds incremental on paper translates into a major challenge on the ground. Meeting this pace of growth is estimated to require $250–$300 billion per year in grid investment, about double what the system has been absorbing.

Where the system starts to strain

The strain appears first in the interconnection queue. It shows up as long waits, backlogs, and delays for connecting new loads and new generation.

Before new generators or large load customers can be connected, a study is required to assess their impact on the grid, whether it can physically handle the added load, and whether upgrades are required. With AI-driven data centers, utilities face far more connection requests than they can realistically support. In ERCOT, large-load interconnection requests exceed 200 gigawatts, most tied to data centers. That amount exceeds historical norms, and it is several times larger than what can be practically studied or built in the near term.

To be clear, public utility commissions are required to study these requests because they must manage system capabilities to ensure minimal disruption. This means engineers spend time evaluating projects that may never be built, while other more commercially viable projects may wait longer for approvals. This extends timelines and makes infrastructure planning less reliable.

Why policymakers are rethinking the rules

Utilities and their regulators must decide how much generation, transmission, and substation capacity to build years before it comes online. Those decisions are based on expected demand at the time projects are approved. When it comes to data centers, by the time infrastructure is completed, they may end up deploying newer, more efficient chips that use less power than originally assumed. This can result in grid infrastructure built for a higher load than what actually materializes, leaving excess capacity that still must be paid for through system-wide rates.

That’s the central dilemma. If utilities build too little capacity, the system operates with less reserve margin. During periods of grid stress, operators have fewer options, increasing the likelihood of curtailments or outages. However, if utilities build too much, customers may be asked to pay for infrastructure that is not fully used.

In response, policymakers are adjusting the rules. In some regions, regulators are moving toward bring-your-own-power approaches that require large data centers to supply or fund part of the capacity needed to serve them or reduce demand during system stress. At the federal level, permitting reforms tied to datacenter infrastructure increasingly treat electricity as a strategic economic input.

As Ken Medlock, senior director at the Baker Institute Center for Energy Studies (CES), explains:

“Many of the planned data centers are now also adding behind-the-meter options to their development plans because they do not anticipate being able to manage their needs solely from the grid, and they certainly cannot do so with only intermittent power sources.”

Behind-the-meter (BTM) refers to power that a consumer controls on its side of the utility meter, such as on-site gas generation or a dedicated power plant. These resources allow data centers to keep operating during grid-related service. Most facilities remain connected to the grid, but the backup BTM generation serves as insurance for operating their core business.

This shifts responsibility. Utilities traditionally manage reliability across all customers by maintaining an operating reserve margin, or spare capacity. Increasingly, large-load customers manage part of their own electricity reliability needs, which changes how infrastructure is planned and how risk is distributed.

Bottom line

AI-driven load growth is arriving faster and in more concentrated places than the power system was built to accommodate. Utilities and regulators are being forced to make decisions sooner than planned about where to build, how fast to build, and which customers get priority when capacity is limited. The effects extend beyond data centers, showing up in system costs, reliability margins, competition for grid access, and pressure on communities and industries that depend on affordable and dependable power. The issue is not whether electricity can be generated, but how the costs and risks of rapid demand growth are distributed as the system tries to keep up. How regulators balance these decisions will determine who pays as AI demand outruns the power grid.

-----------

Scott Nyquist is a senior advisor at McKinsey & Company and vice chairman, Houston Energy Transition Initiative of the Greater Houston Partnership. The views expressed herein are Nyquist's own and not those of McKinsey & Company or of the Greater Houston Partnership. This article originally appeared on LinkedIn.
Greenhouse gases continue to rise, and the challenges they pose are not going away. Photo via Getty Images

Houston energy expert: How the U.S. can turn carbon into growth

Guets Column

For the past 40 years, climate policy has often felt like two steps forward, one step back. Regulations shift with politics, incentives get diluted, and long-term aspirations like net-zero by 2050 seem increasingly out of reach. Yet greenhouse gases continue to rise, and the challenges they pose are not going away.

This matters because the costs are real. Extreme weather is already straining U.S. power grids, damaging homes, and disrupting supply chains. Communities are spending more on recovery while businesses face rising risks to operations and assets. So, how can the U.S. prepare and respond?

The Baker Institute Center for Energy Studies (CES) points to two complementary strategies. First, invest in large-scale public adaptation to protect communities and infrastructure. Second, reframe carbon as a resource, not just a waste stream to be reduced.

Why Focusing on Emissions Alone Falls Short

Peter Hartley argues that decades of global efforts to curb emissions have done little to slow the rise of CO₂. International cooperation is difficult, the costs are felt immediately, and the technologies needed are often expensive. Emissions reduction has been the central policy tool for decades, and it has been neither sufficient nor effective.

One practical response is adaptation, which means preparing for climate impacts we can’t avoid. Some of these measures are private, taken by households or businesses to reduce their own risks, such as farmers shifting crop types, property owners installing fire-resistant materials, or families improving insulation. Others are public goods that require policy action. These include building stronger levees and flood defenses, reinforcing power grids, upgrading water systems, revising building codes, and planning for wildfire risks. Such efforts protect people today while reducing long-term costs, and they work regardless of the source of extreme weather. Adaptation also does not depend on global consensus; each country, state, or city can act in its own interest. Many of these measures even deliver benefits beyond weather resilience, such as stronger infrastructure and improved security against broader threats.

McKinsey research reinforces this logic. Without a rapid scale-up of climate adaptation, the U.S. will face serious socioeconomic risks. These include damage to infrastructure and property from storms, floods, and heat waves, as well as greater stress on vulnerable populations and disrupted supply chains.

Making Carbon Work for Us

While adaptation addresses immediate risks, Ken Medlock points to a longer-term opportunity: turning carbon into value.

Carbon can serve as a building block for advanced materials in construction, transportation, power transmission, and agriculture. Biochar to improve soils, carbon composites for stronger and lighter products, and next-generation fuels are all examples. As Ken points out, carbon-to-value strategies can extend into construction and infrastructure. Beyond creating new markets, carbon conversion could deliver lighter and more resilient materials, helping the U.S. build infrastructure that is stronger, longer-lasting, and better able to withstand climate stress.

A carbon-to-value economy can help the U.S. strengthen its manufacturing base and position itself as a global supplier of advanced materials.

These solutions are not yet economic at scale, but smart policies can change that. Expanding the 45Q tax credit to cover carbon use in materials, funding research at DOE labs and universities, and supporting early markets would help create the conditions for growth.

Conclusion

Instead of choosing between “doing nothing” and “net zero at any cost,” we need a third approach that invests in both climate resilience and carbon conversion.

Public adaptation strengthens and improves the infrastructure we rely on every day, including levees, power grids, water systems, and building standards that protect communities from climate shocks. Carbon-to-value strategies can complement these efforts by creating lighter, more resilient carbon-based infrastructure.

CES suggests this combination is a pragmatic way forward. As Peter emphasizes, adaptation works because it is in each nation’s self-interest. And as Ken reminds us, “The U.S. has a comparative advantage in carbon. Leveraging it to its fullest extent puts the U.S. in a position of strength now and well into the future.”

-----------

Scott Nyquist is a senior advisor at McKinsey & Company and vice chairman, Houston Energy Transition Initiative of the Greater Houston Partnership. The views expressed herein are Nyquist's own and not those of McKinsey & Company or of the Greater Houston Partnership. This article originally appeared on LinkedIn.
What lies ahead over the next year? Photo via Getty Images

Oil markets on edge: Geopolitics, supply risks, and what comes next

guest column

Oil prices are once again riding the waves of geopolitics. Uncertainty remains a key factor shaping global energy trends.

As of June 25, 2025, U.S. gas prices were averaging around $3.22 per gallon, well below last summer’s levels and certainly not near any recent high. Meanwhile, Brent crude is trading near $68 per barrel, though analysts warn that renewed escalation especially involving Iran and the Strait of Hormuz could push prices above $90 or even $100. Trump’s recent comments that China may continue purchasing Iranian oil add yet another layer of geopolitical complexity.

So how should we think about the state of the oil market and what lies ahead over the next year?

That question was explored on the latest episode of The Energy Forum with experts Skip York and Abhi Rajendran, who both bring deep experience in analyzing global oil dynamics.

“About 20% of the world’s oil and LNG flows through the Strait of Hormuz,” said Skip. “When conflict looms, even the perception of disruption can move the market $5 a barrel or more.”

This is exactly what we saw recently: a market reacting not just to actual supply and demand, but to perceived risk. And that risk is compounding existing challenges, where global demand remains steady, but supply has been slow to respond.

Abhi noted that U.S. shale production has been flat so far this year, and that given the market’s volatility, it’s becoming harder to stay short on oil. In his view, a higher price floor may be taking hold, with longer-lasting upward pressure likely if current dynamics continue.

Meanwhile, OPEC+ is signaling supply increases, but actual delivery has underwhelmed. Add in record-breaking summer heat in the Middle East, pulling up seasonal demand, and it’s easy to see why both experts foresee a return to the $70–$80 range, even without a major shock.

Longer-term, structural changes in China’s energy mix are starting to reshape demand patterns globally. Diesel and gasoline may have peaked, while petrochemical feedstock growth continues.

Skip noted that China has chosen to expand mobility through “electrons, not molecules,” a reference to electric vehicles over conventional fuels. He pointed out that EVs now account for over 50% of monthly vehicle sales, a signal of a longer-term shift in China’s energy demand.

But geopolitical context matters as much as market math. In his recent policy brief, Jim Krane points out that Trump’s potential return to a “maximum pressure” campaign on Iran is no longer guaranteed strong support from Gulf allies.

Jim points out that Saudi and Emirati leaders are taking a more cautious approach this time, worried that another clash with Iran could deter investors and disrupt progress on Vision 2030. Past attacks and regional instability continue to shape their more restrained approach.

And Iran, for its part, has evolved. The “dark fleet” of sanctions-evasion tankers has expanded, and exports are booming up to 2 million barrels per day, mostly to China. Disruption won’t be as simple as targeting a single export terminal anymore, with infrastructure like the Jask terminal outside the Strait of Hormuz.

Where do we go from here?

Skip suggests we may see prices drift upward through 2026 as OPEC+ runs out of spare capacity and U.S. shale declines. Abhi is even more bullish, seeing potential for a quicker climb if demand strengthens and supply falters.

We’re entering a phase where geopolitical missteps, whether in Tehran, Beijing, or Washington, can have outsized impacts. Market fundamentals matter, but political risk is the wildcard that could rewrite the price deck overnight.

As these dynamics continue to evolve, one thing is clear: energy policy, diplomacy, and investment strategy must be strategically coordinated to manage risk and maintain market stability. The stakes for global markets are simply too high for misalignment.

------------

Scott Nyquist is a senior advisor at McKinsey & Company and vice chairman, Houston Energy Transition Initiative of the Greater Houston Partnership. The views expressed herein are Nyquist's own and not those of McKinsey & Company or of the Greater Houston Partnership. This article originally appeared on LinkedIn.
U.S. LNG is essential to balancing global energy markets for the decades ahead. Photo via Getty Images

Houston expert: The role of U.S. LNG in global energy markets

guest column

The debate over U.S. Liquefied Natural Gas (LNG) exports is too often framed in misleading, oversimplified terms. The reality is clear: LNG is not just a temporary fix or a bridge fuel, it is a fundamental pillar of global energy security and economic stability. U.S. LNG is already reducing coal use in Asia, strengthening Europe’s energy balance, and driving economic growth at home. Turning away from LNG exports now would be a shortsighted mistake, undermining both U.S. economic interests and global energy security.

Ken Medlock, Senior Director of the Baker Institute’s Center for Energy Studies, provides a fact-based assessment of the U.S. LNG exports that cuts through the noise. His analysis, consistent with McKinsey work, confirms that U.S. LNG is essential to balancing global energy markets for the decades ahead. While infrastructure challenges and environmental concerns exist, the benefits far outweigh the drawbacks. If the U.S. fails to embrace its leadership in LNG, we risk giving up our position to competitors, weakening our energy resilience, and damaging national security.

LNG Export Licenses: Options, Not Guarantees

A common but deeply flawed argument against expanding LNG exports is the assumption that granting licenses guarantees unlimited exports. This is simply incorrect. As Medlock puts it, “Licenses are options, not guarantees. Projects do not move forward if they are unable to find commercial footing.”

This is critical: government approvals do not dictate market outcomes. LNG projects must navigate economic viability, infrastructure feasibility, and global demand before becoming operational. This reality should dispel fears that expanded licensing will automatically lead to an uncontrolled surge in exports or domestic price spikes. The market, not government restrictions, should determine which projects succeed.

Canada’s Role in U.S. Gas Markets

The U.S. LNG debate often overlooks an important factor: pipeline imports from Canada. The U.S. and Canadian markets are deeply intertwined, yet critics often ignore this reality. Medlock highlights that “the importance to domestic supply-demand balance of our neighbors to the north and south cannot be overstated.”

Infrastructure Constraints and Price Volatility

One of the most counterproductive policies the U.S. could adopt is restricting LNG infrastructure development. Ironically, such restrictions would not only hinder exports but also drive up domestic energy prices. Medlock’s report explains this paradox: “Constraints that either raise development costs or limit the ability to develop infrastructure tend to make domestic supply less elastic. Ironically, this has the impact of limiting exports and raising domestic prices.”

The takeaway is straightforward: blocking infrastructure development is a self-inflicted wound. It stifles market efficiency, raises costs for American consumers, and weakens U.S. competitiveness in global energy markets. McKinsey research confirms that well-planned infrastructure investments lead to greater price stability and a more resilient energy sector. The U.S. should be accelerating, not hindering, these investments.

Short-Run vs. Long-Run Impacts on Domestic Prices

Critics of LNG exports often confuse short-term price fluctuations with long-term market trends. This is a mistake. Medlock underscores that “analysis that claims overly negative domestic price impacts due to exports tend to miss the distinction between short-run and long-run elasticity.”

Short-term price shifts are inevitable, driven by seasonal demand and supply disruptions. But long-term trends tell a different story: as infrastructure improves and production expands, markets adjust, and price impacts moderate. McKinsey analysis suggests supply elasticity increases as producers respond to price signals. Policy decisions should be grounded in this broader economic reality, not reactionary fears about temporary price movements.

Assessing the Emissions Debate

The argument that restricting U.S. LNG exports will lower global emissions is fundamentally flawed. In fact, the opposite is true. Medlock warns against “engineering scenarios that violate basic economic principles to induce particular impacts.” He emphasizes that evaluating emissions must be done holistically. “Constraining U.S. LNG exports will likely mean Asian countries will continue to turn to coal for power system balance,” a move that would significantly increase global emissions.

McKinsey’s research reinforces that, on a lifecycle basis, U.S. LNG produces fewer emissions than coal. That said, there is room for improvement, and efforts should focus on minimizing methane leakage and optimizing gas production efficiency.

However, the broader point remains: restricting LNG on environmental grounds ignores the global energy trade-offs at play. A rational approach would address emissions concerns while still recognizing the role of LNG in the global energy system.

The DOE’s Commonwealth LNG Authorization

The Department of Energy’s recent conditional approval of the Commonwealth LNG project is a step in the right direction. It signals that economic growth, energy security, and market demand remain key considerations in regulatory decisions. Medlock’s analysis makes it clear that LNG exports will be driven by market forces, and McKinsey’s projections show that global demand for flexible, reliable LNG is only increasing.

The U.S. should not limit itself with restrictive policies when the rest of the world is demanding more LNG. This is an opportunity to strengthen our position as a global energy leader, create jobs, and ensure long-term energy security.

Conclusion

The U.S. LNG debate must move beyond fear-driven narratives and focus on reality. The facts are clear: LNG exports strengthen energy security, drive economic growth, and reduce global emissions by displacing coal.

Instead of restrictive policies that limit LNG’s potential, the U.S. should focus on expanding infrastructure, maintaining market flexibility, and supporting innovation to further reduce emissions. The energy transition will be shaped by market realities, not unrealistic expectations.

The U.S. has an opportunity to lead. But leadership requires embracing economic logic, investing in infrastructure, and ensuring our policies are guided by facts, not political expediency. LNG is a critical part of the global energy landscape, and it’s time to recognize its long-term strategic value.

------------

Scott Nyquist is a senior advisor at McKinsey & Company and vice chairman, Houston Energy Transition Initiative of the Greater Houston Partnership. The views expressed herein are Nyquist's own and not those of McKinsey & Company or of the Greater Houston Partnership. This article originally appeared on LinkedIn.
Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Houston energy and innovation leaders come together at Argonne National Laboratory

The view from heti

Nearly 20 companies from Houston, ranging from global multinationals to innovative startups, joined the team at Argonne National Laboratory in Lemont, Illinois, for a full day of meetings, discussions, and networking focused on advancing innovation, commercialization, and industry collaboration.

The fly-in organized by the Houston Energy Transition Initiative, provided a unique opportunity for companies to engage directly with Argonne researchers, technical experts, and leadership while gaining a deeper understanding of the laboratory’s world-class capabilities. Participants explored how national laboratories can help bridge the gap between breakthrough research and commercial deployment, particularly in areas critical to U.S. competitiveness and economic growth.

The significance of this engagement extends beyond a single visit. While the U.S. Department of Energy operates 17 national laboratories, none is located along the Gulf Coast, a region uniquely home to industry, infrastructure, and energy systems at commercial scale. HETI’s continued work with the national laboratories helps bridge that geographic and operational gap by connecting world-class scientific research with companies that understand how to scale and deploy technologies. The Argonne fly-in also created space to address practical barriers to collaboration, including complex agreements and lengthy contracting timelines, and to explore ways to establish partnership frameworks more efficiently.

Explore HETI’s key takeaways from the fly-in:

1. Scaling Technologies for Commercial Use

A central theme was the importance of scale-up infrastructure and the role Argonne plays in helping companies reduce technical and manufacturing risks. Participants learned how facilities such as the Materials Engineering Research Facility (MERF) support the transition from laboratory discoveries to pilot-scale production and ultimately commercial manufacturing. These capabilities are especially valuable for companies working to move promising technologies from concept to market.

The discussions also highlighted Argonne’s extensive work in critical materials, battery recycling, advanced manufacturing, and supply chain resilience. Attendees learned about initiatives including the ReCell Center, AI-enabled materials discovery, and advanced modeling tools that can help businesses understand supply chain vulnerabilities and evaluate mitigation strategies. These capabilities have applications across energy, chemicals, manufacturing, semiconductors, defense, and emerging technologies.

2. Creating Pathways for Collaboration

Another key takeaway was the importance of engaging early. Companies do not need to arrive with a fully developed project or solution. Argonne offers multiple pathways for collaboration, including sponsored research, user facility access, technology licensing, pilot-scale testing, and Cooperative Research and Development Agreements (CRADAs). These partnerships help companies access specialized expertise, facilities, and analytical tools that can accelerate innovation and commercialization

3. Building Connections Across Industry and Research

The fly-in reinforced the value of relationship building. Bringing together nearly 20 organizations in one place created meaningful opportunities for collaboration, knowledge sharing, and identifying future projects.

The conversations throughout the day demonstrated a shared commitment to strengthening domestic innovation, developing resilient supply chains, and creating pathways to bring new technologies to market.

———

This article originally appeared on the Greater Houston Partnership's Houston Energy Transition Initiative blog. HETI exists to support Houston's future as an energy leader. Learn more about HETI’s role in advancing solutions and building partnerships to leverage Houston’s industry leadership for an energy-abundant, low-carbon future.

Fervo produces first geothermal power at flagship Utah project

energy milestone

Fervo Energy’s flagship project in Utah just generated its first geothermal power.

The electricity is now flowing to the power grid from one of Cape Station’s three generation units, Houston-based Fervo said in a news release. This represents an early but important milestone for the project, as the unit isn’t scheduled to deliver contracted power until Oct. 1.

The achievement, coming four months after Fervo’s roughly $2.2 billion IPO, demonstrates the viability of enhanced geothermal systems (EGS).

“This is a gamechanger for the geothermal industry. It establishes EGS as the defining new power generation technology of our time, and we believe it shows that the commercial and technical maturity of EGS is ready to meet the urgent need for reliable, clean power,” Tim Latimer, co-founder and CEO of Fervo, said in the release.

The plant’s two other units are scheduled to launch commercial operations on Jan. 1.

The three units make up the project’s 99-megawatt first phase. The next phase, which will add 400 megawatts of capacity, is under construction. The second phase is set to go online in 2028.

Altogether, Cape Station will provide more than 4 gigawatts of capacity, with 900 megawatts already spoken for. The 900 megawatts of contracted electricity would be enough to power nearly 1 million U.S. homes per year.

“Cape Station works because we treated the subsurface like an engineering challenge,” Jack Norbeck, co-founder and chief technology officer of Fervo, added in the release. “Years of drilling, completion design, subsurface modeling, and flow testing led to this moment, and this is the validation that matters most.”

Enhanced geothermal continuously draws on heat that’s deep underground, producing electricity around the clock regardless of weather or time of day. That makes it one of the only carbon-free resources capable of constant power delivery, which is critical for data centers and AI infrastructure.

Expert: Houston Energy and Climate Week showcases a city building the future

guest column

While hundreds of thousands descend on New York for Climate Week, Houston offered a different proposition: come where the work is being built. And last week Houston proved that it’s solving for more energy and fewer emissions; reliability and affordability; speed and durability. We are solving for the “&.”

That equation sharpened last week. On Sept. 14, the Environmental Protection Agency announced it had repealed most 2024 federal carbon-pollution standards for power plants and proposed rescinding remaining greenhouse-gas requirements. Policy matters, but it can pivot. The need to build does not.

HECW is a proving ground, not another conference stop. As I wrote in the Houston Chronicle, Mayor Sylvester Turner planted the seed by insisting we bring people together across the city and industry to drive Houston’s energy future. He knew false choices have no place here: oil and gas and clean technology; prosperity and stewardship; industry and lower emissions.

ECW joined the Climate Week Network this year, connecting Houston to a growing community of more than 500,000 people across 22-plus cities. We now have a seat at the global table—and a responsibility to use it well, building with other cities and the wider clean-energy-solutions world rather than merely talking at them.

The capital is already moving. Since 2017, Houston Energy Transition Initiative member companies have invested more than $95 billion in low-carbon infrastructure, technologies, and research and development. This is where the transition is financed, engineered, tested and operated. But the work requires more than capital. It requires capital allocators who understand the difference between a promising idea and a project that can scale, hire and endure.

Last week was Houston’s show and tell. At ARTECHOUSE, The &Bassador Reception & Awards brought art, technology, culture, philanthropy and energy together. Then the week went beyond downtown.

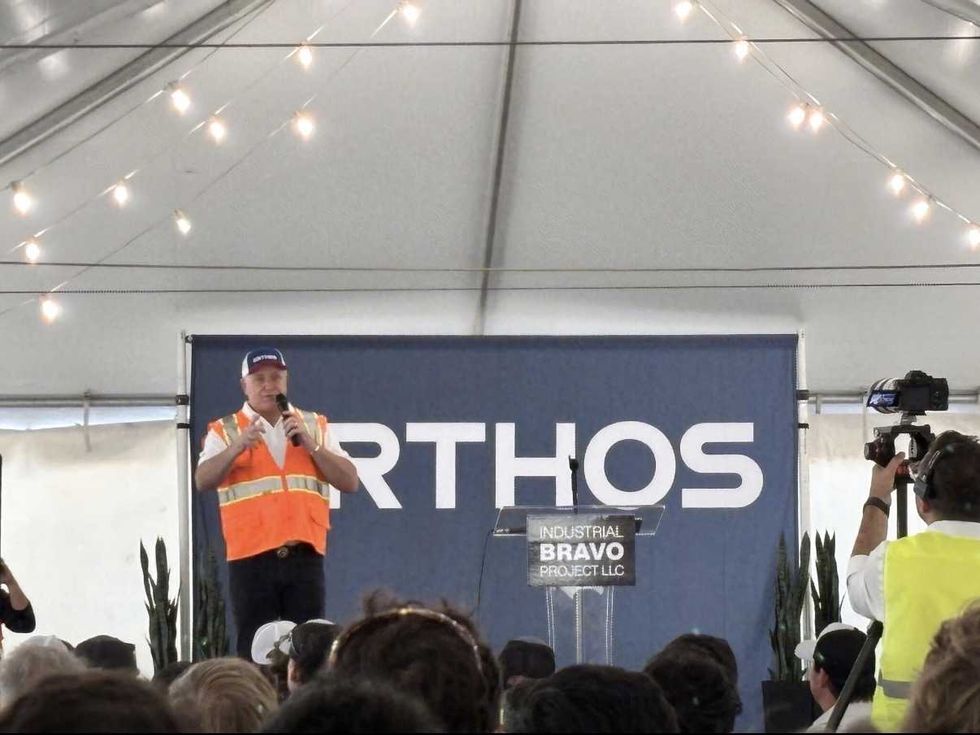
Sugar Land Town Square became the launchpad for the Metro Innovation Tour & Market: a place for an ecosystem conversation about smart cities, clean energy, equitable access and next-generation mobility before participants boarded three tour routes across greater Houston. It was also the starting point for the Bay City South Innovation Tour to Erthos Project Bravo in Matagorda County, where small groups saw Earth Mount solar modules being installed in real time. The conversation did not end at a panel. It went to the project site.

The HTX Tech Tours included a visit to the Erthos Project Bravo in Matagorda County. Photo courtesy

Approximately 100 startups from around the world pitched at Rice Alliance, Greentown Labs and Halliburton Labs events. At Astros Night at Daikin Park, builders, backers, and believers traded conference rooms for the diamond, creating an experience, not just another event. That is how this work becomes civic fabric.

Activation also means making the energy story felt, not merely explained. AY Young brought the Battery Tour for live performances. It was a reminder that the “Power of &” is not confined to a boardroom or a laboratory. Art and technology, culture and commerce, a new generation and established industry can share the same stage—and help more people see themselves in the work ahead.

Perhaps no activation made the “Power of &” more immediate and real than the Houston, We Have Solutions open mic night. At Creatopia’s Innovation Studio, people took the mic—or simply listened—to share what they were building, the problem they could not stop thinking about, and the connection they hoped to make. It put founders, artists, community builders, researchers and future-makers in one room. That is collaboration in real time: different kinds of expertise meeting before anyone knows exactly what the solution will be.

FOX26 helped carry that story beyond the rooms we convened, hosting Erthos COO Jessica Knight, Mars Materials co-founder Aaron Fitzgerald, and investors Taylor Chapman and Juliana Garaizar to discuss building and backing the future in Houston. Our region should be proud—not as self-congratulation, but because the world is beginning to experience energy and climate solutions firsthand.

This was also a week to give back. Allies in Energy awarded $27,500 to nine organizations advancing energy and climate literacy, civil dialogue, workforce pathways and community action. NRG Energy’s Brighter Communities provided a founding gift to expand the week and fund local grants. It took partners, hosts, sponsors, volunteers, funders and community organizations. That is the “Power of &”: collaboration that leaves a stronger community behind.

The “Power of &” cannot stop at Houston’s city limits. Louisiana’s participation—through its support of the Digital Delta Symposium & Expo—made clear that Houston’s builder ecosystem is regional by necessity. Gulf Coast infrastructure, supply chains, talent, and industrial decisions do not recognize state lines. Neither should our collaboration. If we are serious about building more energy with fewer emissions, we must align capital, resources and opportunity across the entire Gulf Coast.

That same commitment to practical collaboration means listening, learning and adjusting. A builder’s mindset does not protect a plan simply because it came first; it improves the conditions for the work to succeed. That is why Houston Energy and Climate Week will move to April 4–10, 2027—better weather, more time and space for connection, and a stronger city-wide experience for the people building what comes next.

But the real test begins now. Can we keep widening the circle? Can we continue to turn research into projects, pilots into infrastructure, capital into good jobs and climate ambition into results that families and communities can see? Can we make every new solution stronger by bringing in the people who must finance it, build it, operate it, live beside it and benefit from it?

That is the work ahead. Turner understood that Houston does not move forward by asking who wins the argument. It moves forward by asking who is ready to solve the problem. His legacy—and the promise of the “&”—is an invitation to choose collaboration over division, action over performance and possibility over false choices.

The future does not need another city to talk about it. It needs Houston to keep building it. And it will only be built if we keep choosing the "&."

---

Katie Mehnert is the CEO of The Bee Suite, and a recent partner to The Builder’s Movement.