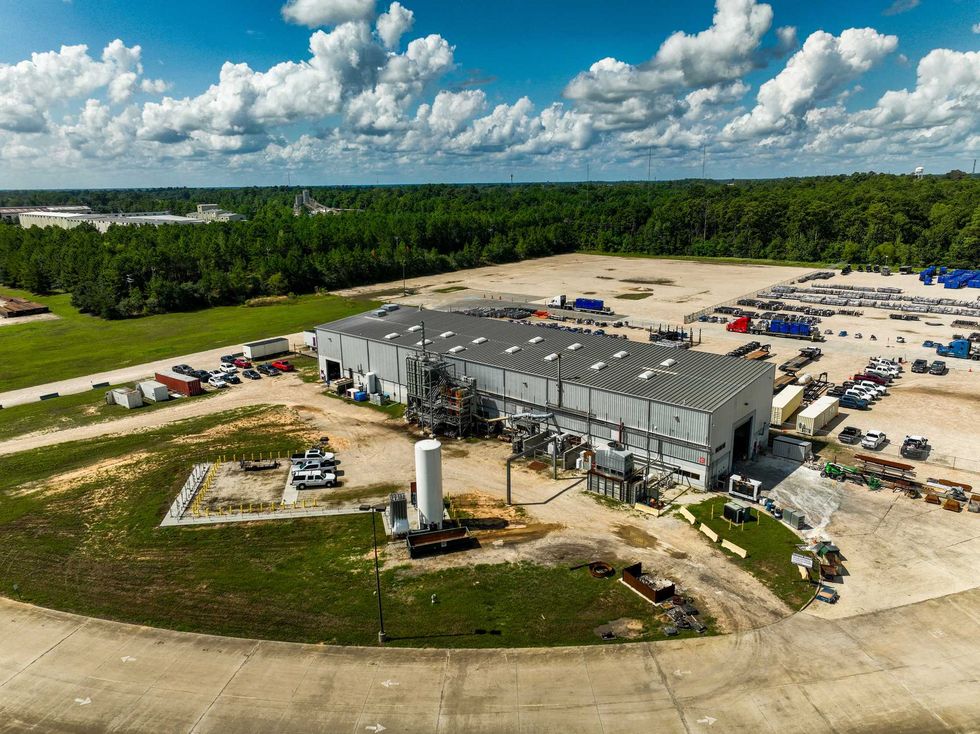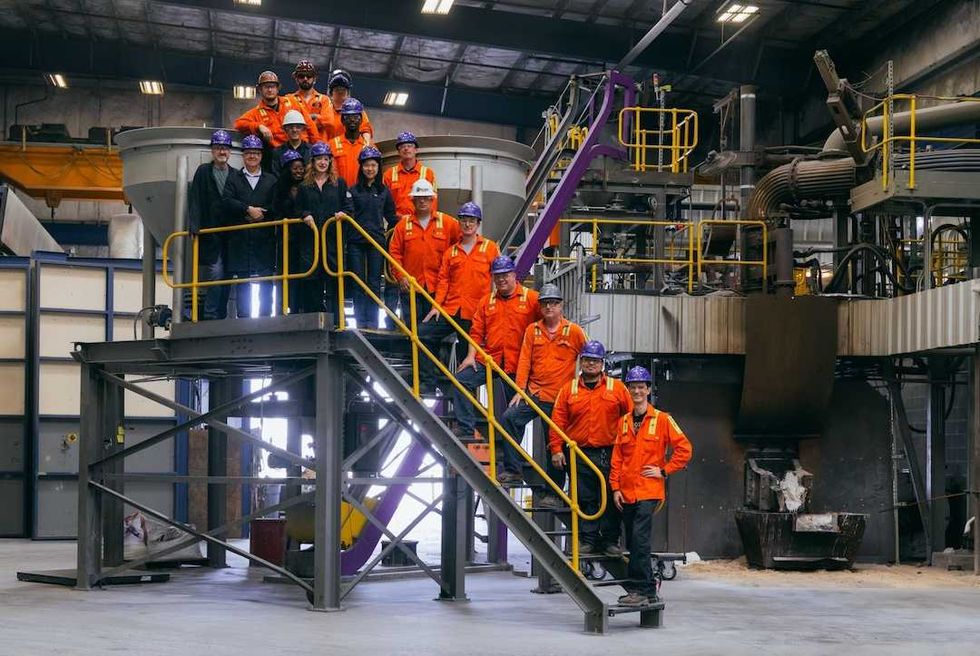
The series A funding will support the deployment of its biochar machines across Texas, Oklahoma, Arkansas, and Louisiana. Photo courtesy of Applied Carbon

A Houston energy tech startup has raised a $21.5 million series a round of funding to support the advancement of its automated technology that converts field wastes into stable carbon.

Applied Carbon, previously known as Climate Robotics, announced that its fresh round of funding was led by TO VC, with participation from Congruent Ventures, Grantham Foundation, Microsoft Climate Innovation Fund, S2G Ventures, Overture.vc, Wireframe Ventures, Autodesk Foundation, Anglo American, Susquehanna Foundation, US Endowment for Forestry and Communities, TELUS Pollinator Fund for Good, and Elemental Excelerator.

The series A funding will support the deployment of its biochar machines across Texas, Oklahoma, Arkansas, and Louisiana.

"Multiple independent studies indicate that converting crop waste into biochar has the potential to remove gigatons of CO2 from the atmosphere each year, while creating trillions of dollars in value for the world's farmers," Jason Aramburu, co-founder and CEO of Applied Carbon, says in a news release. "However, there is no commercially available technology to convert these wastes at low cost.

"Applied Carbon's patented in-field biochar production system is the first solution that can convert crop waste into biochar at a scale and a cost that makes sense for broad acre farming," he continues.

Applied Carbon rebranded in June shortly after being named a top 20 finalist in XPRIZE's four-year, $100 million global Carbon Removal Competition. The company also was named a semi-finalist and awarded $50,000 from the Department of Energy's Carbon Dioxide Removal Purchase Pilot Prize program in May.

"Up to one-third of excess CO2 that has accumulated in the atmosphere since the start of human civilization has come from humans disturbing soil through agriculture," Joshua Phitoussi, co-founder and managing partner at TO VC, adds. "To reach our net-zero objectives, we need to put that carbon back where it belongs.

"Biochar is unique in its potential to do so at a permanence and price point that are conducive to mass-scale adoption of carbon dioxide removal solutions, while also leaving farmers and consumers better off thanks to better soil health and nutrition," he continues. "Thanks to its technology and business model, Applied Carbon is the only company that turns that potential into reality."

The company's robotic technology works in field, picking up agricultural crop residue following harvesting and converts it into biochar in a single pass. The benefits included increasing soil health, improving agronomic productivity, and reducing lime and fertilizer requirements, while also providing a carbon removal and storage solution.

"We've been looking at the biochar sector for over a decade and Applied Carbon's in-field proposition is incredibly compelling," adds Joshua Posamentier, co-founder and managing partner of Congruent Ventures. "The two most exciting things about this approach are that it profitably swings the agricultural sector from carbon positive to carbon negative and that it can get to world-scale impact, on a meaningful timeline, while saving farmers money."

What is it going to take to make Houston a leader in the energy transition? Access to capital, according to a panel from Venture Houston. Photo by Natalie Harms/EnergyCapital

Experts: Houston needs to unlock early-stage capital to lead the energy transition

show me the money

Last week, Tim Latimer sat on a panel that consisted mostly of his company's investors and discussed what he felt the missing piece still was for Houston's energy transition and innovation community.

“There’s no better place in the world than Houston to build and scale a climate tech startup," he says on a Venture Houston panel titled Seeding Sustainability: Unlocking the Power of Early Stage Investments.

“But I don’t know if I’m ready to make the claim that we’re the best place to start a business,” he adds.

Latimer, who co-founded Fervo Energy in the Bay Area in 2017 before relocating the company to Houston, explains that his company raised capital on the West Coast ahead of moving to Texas to grow and scale. This allowed the company, which recently announced the success of a major pilot, to tap into early stage funding and then make the most of every dollar raised by moving to a region where the money would last longer — and where there's talent, customers, and more.

“The dream for us to have a truly unlocked ecosystem is that the whole pattern can happen here in Houston, and the gap I see is that capital formation side,” he says.

Latimer was joined on the panel by some of Fervo's investors: Mark Cupta, managing partner of Prelude Ventures; Andrea Course, venture principal of Shell Ventures; and Joshua Posamentier, co-founder and managing partner of Congruent Ventures.

Each of the panelists weighed in on what it would take for Houston to emerge as a leader within the global energy transition. Cupta says that it's going to take the city time to build out activity, successful outcomes, talent, money, and more.

“The venture capital community is an ecosystem, and that ecosystem consists of multiple stakeholders that all have to work in concert with each other," he says. "It has to be a flywheel that spins up over time.”

Course, the only Houston-based investor on the panel, says that Houston has potential because it's got talent, industry, and money, or TIM, as she describes.

“I think Houston is actually the perfect place for becoming the energy transition capital. If you ask me, I think we already are.” Course explains. “It really just takes people doing what we’re doing now to make it even greater."

Posamentier, who previously shared his outlook on Houston in a Q&A with EnergyCapital, explains that access to funding isn't the only issue. “There’s a lot more money than there are investable opportunities at the moment,” he says.

The panel also weighed in on the difference between venture capital and funding coming out of corporations.

“VCs and CVCs have different timelines,” Course explains, saying VC firms have 5- to 7-year life cycles. After that, they need to see an exit to be able to provide that return. “With a CVC, we don’t really have that. Of course we want to show financial returns, but we are long-duration capital.

CVC is patient capital with value-add investors, but Course admits there's a longer due diligence because she wants to find a strategic stakeholder before an investment is made.

“The worst thing that could happen is that Shell gives you money, but they don’t give you business. We don’t want that,” she says.

Waiting for that right investor can be extremely important to company success, Latimer says from the founder perspective.

“It’s hard to put a hard dollar value on help, but our ability to have advisers and introductions from different types of investors … makes all the difference in the world,” he says on the panel. “A lot of startup founders think about their org design very critically and who they want to bring onto the team, and you should be deliberate on your cap table.”

Josh Posamentier, co-founder and managing partner at Congruent Ventures, will join Venture Houston as a speaker this year. Photo via congruentvc.com

Sustainability investor addresses startup challenges, Houston's capital shortages, and more

Q&A

It's been a challenging year for venture capital, but how are climatetech startups doing specifically? One Bay Area investor shares his point of view on this this topic ahead of Venture Houston next week.

Joshua Posamentier, co-founder and managing partner of Congruent Ventures, a San Francisco-based firm that invests in early-stage sustainable companies, is taking the stage at Venture Houston on September 7. Among others, Posamentier will be in conversation with the founder of one of his firm's portfolio companies, Fervo Energy, discussing seed and early-stage funding for sustainability-focused startups.

Venture Houston is presented by HX Venture Fund, a fund of funds that deploys capital into non-Houston firms to encourage investment in local startups. This year's theme is "Spotlighting the path for decarbonization in a digital world."

Posamentier, who has worked over a decade in this space, shares some of his thoughts on Houston as an energy transition leader, the challenges climate-tech startups face, and more in an interview with EnergyCapital.

EnergyCapital: How do you see Houston and its role in this energy transition, its challenges, its opportunities, etc.?

Josh Posamentier: I actually tend to disagree with the people that say Houston is too far down the oil and gas path. I mean, it's it's capitalism at the end of the day. There's money to be made in in climate mitigation technologies. People are going to go chase it, and I think Houston, of all places, is a pretty capitalistic city. And people are definitely not shy about chasing the next big opportunity. I mean, it was oil and natural gas before, and now it's now it's alternative energy. And so I think from that perspective, it's fine. There's a lot of money.

I think the biggest challenge is honestly, especially on a perception basis, a lot of the policy and social stuff that's endemic to Texas, which is a bummer. I mean, especially for younger talent. Austin had a shine, but I think that's largely gone and Houston never had it. So, I think it's something that needs to be overcome and needs to be thought about at a state level basis, especially if you're going to want to attract young entrepreneurial talent.

EC: What are some of the challenges energy transition startups are facing these days? How is your fund kind of supporting your portfolio companies through these challenges?

JP: There's some normalization that's had to happen over the last 9 to 12 months. As you know, corrections have come down the pipe in the venture ecosystem. By all accounts, it has been really frothy for the last few years, especially so in parts of climate. Some of that's due to the the proliferation of investment from non climate-specific firms. And it's, in many ways, decoupled from the ups and downs of different parts of the venture ecosystem, but it also has different timelines. I think not everyone always appreciates what that means and what that implies for for startups. So there's a lot of frustration and a lot of missed expectations in the early stage part of the ecosystem that are slowly getting fixed. I think getting expectations more in line with reality is going to help immensely.

The other thing is just figuring out how to talk more in a language that venture investors understand. I think that's a little bit of a challenge. There's there's actually a pretty big gap between if you're an oil and gas developer and thinking about how you fund that kind of a business versus how you fund a technology-enabling business. Fervo Energy is an interesting example. It's a tech company, but now it's really a tech enabled developer because they have no choice but to do that full stack. They went to school out here. They understand the ecosystem. They've really taken the effort to really understand all the capital players. And so we're waiting to see how that ultimately plays out.

But there's just different capital. I think it is a little challenging. And this is a good thing. There does need to be a way, I think, to just get people more exposure to to the market there — in the Houston market specifically. If you're spinning at Stanford, there are hundreds of VCs within walking distance. In Houston, the ones I know I can count on one hand.

EC: Has that pace of commercialization changed over the years or have founders found ways to survive that valley of death?

JP: I don't think anything's really changed fundamentally. I think people have gotten a little more clever about understanding how the adoption occurs, and figuring out how to phase into those processes that that comes with experience. But there's only so much acceleration you can do when you're dealing with critical infrastructure. You know, people are not going to want to just jump right in, rip out, and replace things that keep the lights on. And so you just have to figure out how to how to capitalize a business in such a way that you can you can live with those kinds of timelines. Venture capital is a fantastic tool, and it is far from the right tool for every problem. And so there are plenty of opportunities to deploy other tools that are more appropriate to different kinds of different kinds of challenges.

EC: What attracted you to investing in Fervo Energy?

JP: So, it's how we think about portfolio construction. Fervo has an amazing team, which we will bend a lot of rules for, and we saw this opportunity as something they could build a ton of value by validating the tech, establishing a huge land position, and then raising different kinds of capital for the out years and for the project development. A bunch of our companies took venture capital to develop a technology, and then they know that venture is not the right class of capital to then scale that throughout the world and whatever. So they would basically raise other forms of capital in the out years to deploy the technologies.

EC: And one of those options is government funding. How do your portfolio companies utilize that?

JP: A big chunk of our portfolio has some government money, even if it's very early stage research grants or something like that. I see government money being the most effective in a couple of ways. One way obviously is to get the core research out of it versus just spin it into something more commercial that we can all then look at.

The other place that is really exciting is in is getting technologies to scale where they're then cost effective without further subsidies. When we underwrite companies, we are very explicitly underwriting them in the absence of subsidies at scale. The assumption is those are just there to basically bridge the gap between "this is totally uneconomic because it's a tiny, tiny little factory or something" versus "it would be plenty economic if it were a big factory." So, if they can just bridge that gap with a little bit of government money.

We've been through this this cycle a couple of times, and we can't in good faith underwrite anything assuming that government subsidies are going to continue. We very much believe it's a bridge — it's got to be a bridge to something. It can't be a bridge to nowhere. And I think there are a lot of companies out there today that are almost designed to just pump the government incentives, and that's not a recipe for a business that can grow on its own over time.

------

This conversation has been edited for brevity and clarity.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Houston researchers develop compact carbon capture tech for data centers

AI emissions

Two scientists from the University of Houston have been experimenting with new carbon capture systems that fit inside a standard shipping container, which have the potential to make eliminating carbon output from industrial sites much easier.

The capture of industrial carbon is an important complement to the fight against climate change, as well as winning tax credits for businesses that use carbon capture technology.

The problem is that such systems are often measured in acres, making them expensive to build and extremely power-hungry to actually use. UH Engineering Professor Mim Rahimi and former UH Ph.D. student Ahmad Hassan (now a postdoctoral associate at Harvard) have managed to fit their new system, the Small Modular Electrochemical Container (SMECs), inside a standard 40-foot shipping crate, making them compact and modular enough to be installed almost anywhere for operations of all sizes. Their research was recently published in the journal Environmental Science & Technology.

“With a conventional system, you’re building a 130-foot-tall structure designed for a specific power plant. With our technology, we can adjust the capacity by simply turning containers on or off,” Rahimi said in a news release. “That flexibility is particularly important for data centers, where electricity can come from a combination of natural gas and renewable sources.”

Rahimi and Hassan used simulated gas models to show that under optimal conditions, the SMEC used electrochemically mediated amine regeneration (EMAR) cells developed in Rahimi’s lab to capture 90 percent of carbon under optimal conditions through 300 cycles over 50 hours.

Encouraged, the team then modeled a 360-megawatt natural gas power plant associated with OpenAI’s Stargate AI data center project in Abilene, Texas. In addition to the savings on infrastructure costs, 20 of the researchers’ shipping container systems were able to capture 98 percent of carbon from Stargate’s 875-acre campus based on the model.

The looming energy costs and subsequent carbon emissions from data centers are a real concern. Estimates from the U.S. Department of Energy hypothesize that 12 percent of America’s energy needs could be gobbled up by the centers as soon as 2028. That is a massive new source of carbon. The flexibility of the SMEC means they can be deployed wherever the centers spring up.

“We’re taking a technology that traditionally requires enormous infrastructure and finding a way to fit it inside a shipping container,” Rahimi added in the release. “That opens up entirely new possibilities for how and where carbon capture systems can be used.”

In the future, the researchers say they plan to look at ways to adapt the technology to capture carbon dioxide directly from the atmosphere.

Hertha Metals breaks ground on $100M high-purity iron factory in Conroe

coming soon

Shortly after announcing a $133.65 Series A funding round, Conroe-based Hertha Metals broke ground Oct. 8 on a $100 million factory that will produce steel-grade and magnet-grade high-purity iron.

Hertha’s Chalyx plant, located in Conroe, will manufacture a total of about 10,000 metric tons per year of magnet-grade and steel-grade high-purity iron. The factory will use Hertha’s single-step process to generate high-purity iron for rare-earth-magnet and steel manufacturers in the U.S.

Hertha says Chalyx will be the first U.S. commercial plant for production of magnet-grade high-purity iron.

Chalyx is being built next to Hertha’s headquarters and its Pi100 pilot plant, which will remain in operation. Chalyx and Pi100 will form the first modern-day iron and steel “innovation complex” in the U.S., the company says.

“I founded Hertha Metals because I believed we could significantly improve how the world makes iron and steel from ore, and that an industry so fundamental to our future still had enormous room for invention,” Laureen Meroueh, founder and CEO of Hertha, said in a press release.

The 4-year-old startup says the Chalyx complex will lay the foundation for its first 500,000-ton-per-year steel mill.

Chalyx’s first priority is making high-purity iron for U.S. manufacturers of rare-earth magnets, Hertha says. These magnets are critical components for electric vehicles, data centers, wind turbines and defense systems.

China produces an estimated 94 percent of high-purity iron for rare-earth magnets, according to Hertha.

Aside from iron for rare-earth magnets, Chalyx will make iron and steel for pilot projects in the steel industry.

The plant is expected to come online in late 2027, with production of magnet-grade high-purity iron starting in early 2028.

Today, Hertha employs 32 people, the company says. Once it’s fully operating, the Chalyx plant will employ about 50 people.

Just ahead of the groundbreaking, Hertha announced the $133.65 million Series A round, co-led by Khosla Ventures and Doerr Capital. The round included a $65 million equity investment from the Pentagon.

“Iron and steel have shaped human progress for thousands of years. And I believe there is still an enormous amount left to invent,” Meroueh said at the groundbreaking ceremony.

Canada-founded energy tech company moves global HQ to Energy Corridor

houston hq

Pulsed-power technology company BlueSpark Energy will open its new global headquarters in Houston’s Energy Corridor to house its engineering, research and development, manufacturing, commercial and digital teams.

“Houston isn’t simply our new headquarters; it’s where a new BlueSpark begins,” Kahina Abdeli-Galinier, president and CEO of BlueSpark, said in a news release. ”We’re building the well health technology the industry needs to get more from existing wells, reduce intervention costs and keep wells producing for longer. Our new home brings us closer to our customers and places us at the heart of one of the most exciting markets in the industry, with the talent pool to match.”

The company, which began in Calgary, plans to grow its Houston workforce to 100 employees by the end of 2028, while the manufacturing element is expected to be operational in February 2027.

According to BlueSpark, the new facility will feature double the manufacturing floorspace of its current site, and the extra space will allow it to scale its tool manufacturing.

The headquarters is on West Sam Houston Parkway. BlueSpark's Chief Technology Officer Matt Mohajer and Chief Commercial Officer Zach Wilbur are already leading teams at the new space, according to the release.

BlueSpark develops pulsed-power technology that uses electrical energy to clean oil and gas well components, remove scale buildup and restore production without damaging equipment. Its technology helps operators reduce downtime, improve well performance and extend the productive life of existing wells.

Late last year, the company named Kahina Abdeli-Galinier as its CEO. It has since rebranded and focused on expanding its technology into new applications, including plugging and abandonment, cement removal and water services.

“We’re investing heavily in our technology, both the physics and the intelligence and delivery layer around it,” Abdeli-Galinier added in the release. “Having our engineering, manufacturing, digital, R&D and commercial teams in one place allows us to move much faster, giving our customers the tools they need to keep wells healthy and producing more for longer.”