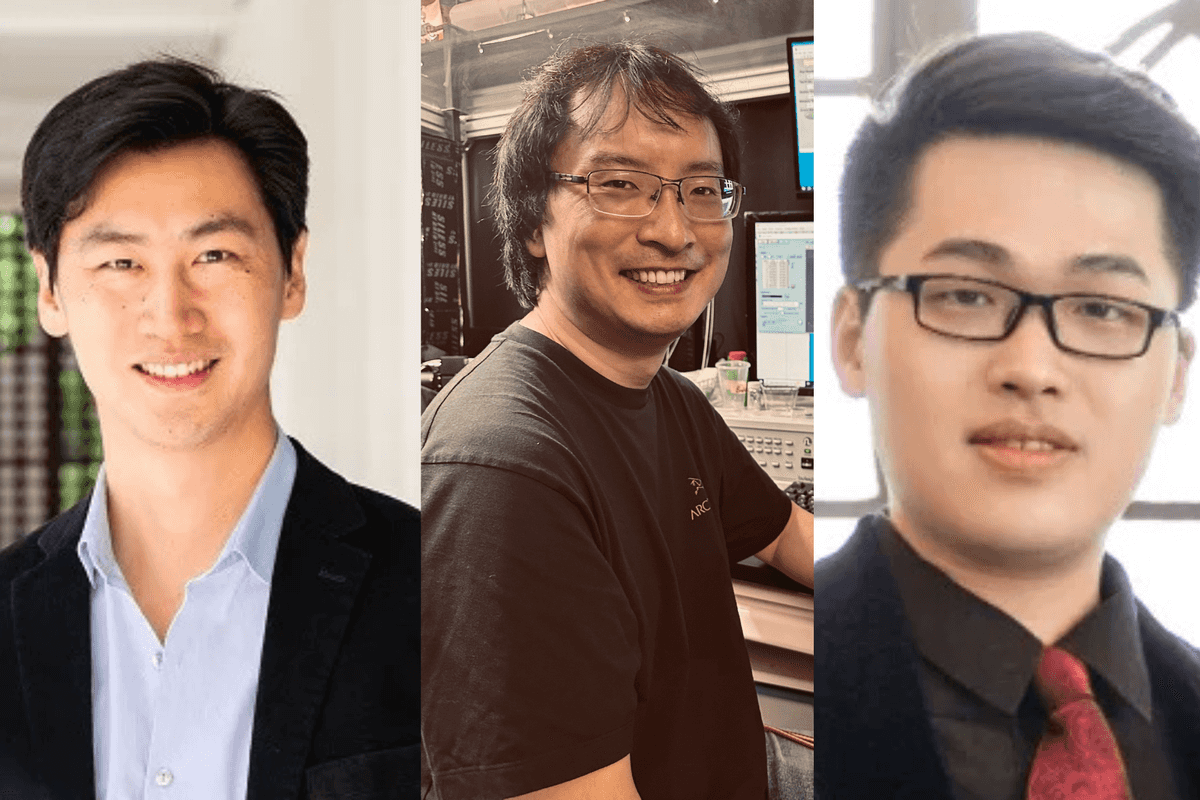
Al Vickers, XGS Energy's new COO, and Richard Chong, the company's new CFO. Photos courtesy XGS/LinkedIn

XGS Energy, a Houston-based developer of geothermal power systems, has added several energy industry veterans to its C-suite this summer.

The company named Al Vickers as its new chief operating officer earlier this month. Vickers will replace Ghazal Izadi in the role, as she moves into the chief growth officer position.

Vickers previously served as CEO of BP's U.S. Low Carbon Energy business and most recently was COO of Houston-based Grid United, which develops next-generation transmission infrastructure.

“I have spent my career developing, building, and operating large, complex energy infrastructure, and I am excited to work with XGS’s proven technology, which is ready to deliver clean, round-the-clock power at the scale the grid and customers need,” Vickers said in a news release. “XGS sits at the intersection of innovation, affordability, demand growth, responsible infrastructure development, and long-term energy resilience. I’m excited to roll up my sleeves and apply best practices from both oil and gas and infrastructure development to deliver gigawatt-scale geothermal projects.”

Kurt Fricker, who most recently held leadership roles at Hess Corporation, was also announced as XGS's new chief procurement officer.

The hires come shortly after XGS announced Richard Chong as its new chief financial officer in May.

Chong joins XGS from Houston-based power producer Calpine, where he most recently was vice president of finance. His work there included leading $2.25 billion in financing for Geysers, the world’s largest geothermal power complex.

Chong says XGS’ proven technology and the rising demand for clean power will help the company execute on its multi-gigawatt pipeline.

“I look forward to applying the experience I’ve built over two decades in energy finance to help XGS deliver clean, reliable power to customers and unlock the massive development opportunity ahead for next-generation geothermal,” Chong said in the release.

XGS’ first project is a 150-megawatt geothermal facility in New Mexico. It will supply around-the-clock electricity to the grid operated by Public Service Co. of New Mexico in support of Meta data centers.

XGS recently tapped Houston-based energy technology company Baker Hughes to provide engineering services for the New Mexico project.

XGS’ geothermal system uses thermally conductive materials to deliver affordable energy anywhere hot rock exists — without the need for water resources or specific geological conditions. This results in lower-risk projects, more site options, easier permitting and faster deployment.

Since 2023, XGS has raised nearly $57 million in venture capital.

XGS launched in 2008 in Palo Alto, California, as Geothermic Solution. In conjunction with its Series A round in 2023, the company rebranded to its current name. The company recently moved its headquarters to Houston, according to the Houston Business Journal.
With the deal, Chevron gets access to one of the biggest oil finds of the decade. Photo via Chevron

Chevron gets green light on $53 billion Hess acquisition

Mega Deal

Chevron has scored a critical ruling in Paris that has given it the go-ahead for a $53 billion acquisition of Hess and access to one of the biggest oil finds of the decade.

Chevron said Friday that it completed its acquisition of Hess shortly after the ruling from the International Chamber of Commerce in Paris. Exxon had challenged Chevron’s bid for Hess, one of three companies with access to the massive Stabroek Block oil field off the coast of Guyana.

“We disagree with the ICC panel’s interpretation but respect the arbitration and dispute resolution process,” Exxon Mobil said in a statement on Friday.

Guyana is a country of 791,000 people that is poised to become the world’s fourth-largest offshore oil producer, placing it ahead of Qatar, the United States, Mexico and Norway. It has become a major producer in recent years.

Oil giants Exxon Mobil, China’s CNOOC, and Hess squared off in a heated competition for highly lucrative oil fields in northern South America.

With Chevron getting the green light on Friday, it is now one of the major players in the Stabroek.

“We are proud of everyone at Hess for building one of the industry’s best growth portfolios including Guyana, the world’s largest oil discovery in the last 10 years, and the Bakken shale, where we are a leading oil and gas producer,” former Hess CEO John Hess said in a statement. “The strategic combination of Chevron and Hess creates a premier energy company positioned for the future.”

Chevron also said that on Thursday the Federal Trade Commission lifted its earlier restriction, clearing the way for John Hess to join its board of directors, subject to board approval.

Chevron announced its deal for Hess in October 2023, less than two weeks after Exxon Mobil said that it would acquire Pioneer Natural Resources for about $60 billion.

Chevron said at the time that the acquisition of Hess would add a major oil field in Guyana as well as shale properties in the Bakken Formation in North Dakota.

“Given the significant value we’ve created in the development of the Guyana resource, we believed we had a clear duty to our investors to consider our preemption rights to protect the value we created through our innovation and hard work at a time when no one knew just how successful this venture would become,” Exxon Mobil said Friday. “We welcome Chevron to the venture and look forward to continued industry-leading performance and value creation in Guyana for all parties involved.”

Chevron's stock rose more than 3% before the market open, while shares of Hess surged more than 7%. Exxon's stock climbed slightly.

Chevron has a new speed bump on the road to a big acquisition. Photo via Chevron

Chevron's $53B acquisition of Hess Corp. sees hiccup

speed bump

Chevron warned Monday that its pending $53 billion acquisition of Hess may be in jeopardy because it will require the approval of Exxon Mobil and a Chinese national oil company, which both hold rights to development of an oil field off the coast of the South American nation Guyana.

The disclosure in a filing with the Securities and Exchange Commission raised investor qualms, depressing shares of both Chevron and Hess. Chevron's stock price fell 3% Tuesday morning before rebounding; Hess stock lost 4% of its value but bounced back slightly.

Chevron's acquisition of Hess would add this major oil field in Guyana as well as shale properties in the Bakken Formation in North Dakota. Guyana is a country of 791,000 people that is poised to become the world’s fourth-largest offshore oil producer, placing it ahead of Qatar, the United States, Mexico and Norway. It has become a major producer in recent years, with oil giants including Exxon Mobil, China’s CNOOC, and Hess squared off in a heated competition for highly lucrative oil fields in northern South America.

Chevron said it's been engaged in discussion with Exxon and CNOOC, aka China National Offshore Oil Co. Both companies hold rights of first refusal for decisions regarding the oil field in question, known as the Stabroek Block. Exxon Mobil operates the Stabroek Block and holds 45% interest. Hess holds 30% interest, and CNOOC holds the remaining 25% interest. Production capacity at the field is expected to reach more than 1.2 million barrels per day by the end of 2027, Exxon said in November.

If those discussions and subsequent arbitration fail to set aside those first refusal rights, Chevron said, “the merger would not close.”

Companies including Houston-based Chevron and Hess and BP, each with a Houston presence, offered bids. Photo via Getty Images

Houston oil companies offer $382M for drilling rights in Gulf of Mexico in last offshore sale before 2025

for sale

Last month, oil companies offered $382 million for drilling rights in the Gulf of Mexico on Wednesday after courts rejected the Biden administration's plans to scale back the sale to protect an endangered whale species.

The auction was the last of several offshore oil and gas lease sales mandated under the 2022 climate law. It comes as President Joe Biden’s Democratic administration tries to navigate between energy companies seeking greater oil and gas production and environmental activists who want to stop new drilling to help combat climate change.

Companies including Houston-based Chevron and Hess and BP, each with a Houston presence, offered bids on more than 300 parcels covering 2,700 square miles (7,000 square kilometers), according to the U.S. Department of Interior's Bureau of Ocean Energy Management.

The dollar amount of the successful bids marked a sharp increase from the previous sale in March 2023, when the Interior Department awarded leases covering about 2,500 square miles (6,500 square kilometers) for $250 million.

The next sale will be conducted in 2025, to the frustration of energy companies and Republicans who say the administration is hampering U.S. oil production.

Wednesday's online auction was originally scheduled for September but got delayed by a court battle after the administration reduced the area available for leases from 73 million acres (30 million hectares) to 67 million acres (27 million hectares) as part of a plan to protect the endangered Rice’s whale.

Chevron, Shell Offshore, the American Petroleum Institute and the state of Louisiana sued to reverse the cut in acreage and block the inclusion of the whale-protecting measures in the lease sale provisions.

A federal judge in southwest Louisiana ordered the sale to go on without the whale protections, which also included regulations governing vessel speed and personnel. Environmental groups appealed, but the New Orleans-based 5th Circuit Court of Appeals last month rejected their arguments against the sale and threw out the plans to scale it back.

The lease sale was required under a compromise with Democratic Sen. Joe Manchin of West Virginia, a supporter of the oil and gas industry who cast the deciding vote in favor of the landmark climate law. The measure was approved with only Democratic votes in Congress. Under the terms negotiated by Manchin, the government must offer at least 60 million acres of offshore oil and gas leases in any one-year period before it can offer offshore wind leases that are part of its strategy to fight climate change.

Only a small portion of parcels that are offered for sale typically receive bids, in areas where companies want to expand their existing drilling activities or where they foresee future development potential.

The administration in September proposed up to three oil and gas lease sales in the Gulf of Mexico over the next five years and none in Alaska waters. That was the minimum number the administration could legally offer if it wants to continue expanding offshore wind development.

Environmental groups criticized the five-year plan as a “missed opportunity” to stop the expansion of oil and gas drilling in the Gulf of Mexico and address climate change.

“New oil and gas operations (in the Gulf) will only bring more health risks to Gulf Coast communities and slow our transition to a clean-energy economy,'' said Earthjustice attorney Brettny Hardy.

The industry, meanwhile, said more sales are needed — and sooner.

“In our forward-thinking industry, securing new lease blocks is vital for exploring and developing resources crucial to the U.S. economy,'' said National Ocean Industries Association President Erik Milito. “The Gulf of Mexico is a prime economic engine and investment area, and this (lease sale) was the last chance for companies to secure leases in the near term.''

Holly Hopkins, API vice president of upstream policy, called Wednesday's sale "a "positive step after multiple delays,'' and noted that it generated the highest dollar value for bids in nearly a decade.

The results demonstrate that the oil and gas industry “is working to meet growing demand and investing in the nation’s long-term energy security,'' Hopkins said. “Just as today’s record U.S. production was supported by investment and policy decisions made years ago, new leasing opportunities are critical for maintaining American energy leadership for decades to come.''

The administration's clean-energy ambitions have been hampered by recent project cancellations including two large wind projects shelved last month off the New Jersey coast and the earlier cancellation of three projects that would have sent power to New England.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Houston alliance launches effort to establish Gulf Coast national energy lab

energy innovation

Houston energy stakeholders are setting plans in motion to advance a new national laboratory on the Gulf Coast focused on energy and industrial technologies.

The proposed U.S. Department of Energy national lab, known as the Gulf Coast National Laboratory (GCNL), would build on work launched by the Greater Houston Partnership's Houston Energy Transition Initiative (HETI), according to a news release. Founding academic members include Rice University and the University of Houston. Plans for the lab and the new Gulf Coast National Laboratory Alliance were announced at an event at the GHP's Partnership Tower on Nov. 12.

The GCNL's main goal would be bridging the gap between the research and development of promising energy technology and commercialization. It would aim to provide shared pilot facilities, integrated process-scale testing and public-private partnerships.

Focus areas would include:

  • Subsurface technologies
  • Produced water management
  • Process engineering and scale-up
  • Industrial process engineering and supply chains

"The United States has extraordinary research capabilities, but too many promising technologies struggle to cross the gap between proof-of-concept and commercial success," Jane Stricker, executive director of the GCNLA and former executive director of HETI, said in the release. "Our mission is to bring together the organizations and leaders needed to create a scale-up platform that enables technologies to move from innovation to industry faster, more cost-effectively, and at a scale that strengthens U.S. energy security, industrial productivity, and supply-chain resilience."

The new lab will also complement existing DOE labs, which "execute long-term government missions and develop unique scientific capabilities that often extend beyond the scope of academic and industrial institutions," according to the organization's website. There are currently 10 DOE national labs, including the likes of the Ames National Laboratory, the Argonne National Laboratory, the Pacific Northwest National Laboratory and others.

Organizers say the proposed GCNL would serve as "the nation's premier scale-up and deployment platform for energy and industrial technologies." They add that the Gulf Coast is primed for a lab due to the high concentration of energy and industrial infrastructure in the area.

According to the release, Texas produces approximately 43 percent of the nation’s crude oil and the Gulf Coast is home to nearly half of the country's refining capacity.

"By bringing together industry, academia, and government partners, we can reinforce the Gulf Coast's position as the nation's leading energy and industrial hub while advancing U.S. competitiveness and energy security," Steve Kean, president and CEO of the GHP, added in the release.

Organizers are calling on energy companies, academic institutions, investors and other groups to partner on the initiative. There are currently about 20 members of the alliance supporting the lab, ranging from energy giants to venture capital groups and Houston startups.

Current members include:

  • Artemis Energy Partners
  • Baker Hughes
  • Cemvita
  • Dow
  • Energy Transition Ventures
  • ExxonMobil
  • Flour
  • Greater Houston Partnership
  • Greentown Labs
  • HETI
  • LyondellBasell
  • Mitsubishi Heavy Industries
  • New Climate Ventures
  • Rice University
  • San Jacinto College
  • SCF Partners
  • SLB
  • Solidec
  • Syzygy Plasmonics
  • Texas Southern University
  • The University of Houston
  • Via Separations

Houston’s Fervo Energy amasses $12B backlog of orders

q3 results

Houston-based geothermal power company Fervo Energy saw a 65 percent spike in purchase orders during the third quarter.

During Fervo’s third-quarter earnings call, Tim Latimer, co-founder, chair, president and CEO, said the company had a $11.9 billion backlog of orders, up from $7.2 billion in the previous quarter.

Those numbers didn’t translate to robust financial results in the third quarter, though. It closed the quarter with an operating loss of $43 million on revenue of just $116,000.

Beyond the billions of dollars in signed purchase agreements, Fervo is in talks with prospective customers in the utility, industrial data-center sectors, Latimer said. About half the potential customers are in the data-center sector, 35 percent in the utility sector and 15 percent in the industrial sector.

Latimer said the broad-based demand reflected by the backlog and the discussions with potential customers reinforces the critical need for reliable, readily available power.

“Our approach to power delivery will continue to blend front-of-the-meter and behind-the-meter development,” he said. “Grid-connected assets remain the foundation, though behind-the-meter gives customers a faster path to power when transmission time lines lag their need.”

Front-of-the-meter refers to power plants, utility-scale solar and wind farms, large grid batteries, and transmission and distribution infrastructure. Behind-the-meter assets sit on the customer side of the meter, such as backup generators and EV chargers at homes, businesses, factories and other everyday places.

The order backlog isn’t Fervo’s only recent milestone. In late September, the company’s Cape Station geothermal plant in Utah started delivering its first utility-scale geothermal power to the grid. The plant is producing about 33 megawatts of power.

Earlier in September, Fervo signed a 15-year deal to supply about 396 megawatts of power for Google data centers. The power will be delivered in four 99-megawatt batches. The company filed its $1.89 billion IPO this spring.