Michael Wortley, Joulent's new CFO, and Corey Grindal, the company's new COO. Photos courtesy Joulent

Houston-based energy infrastructure startup Joulent has brought aboard a new chief financial officer and new chief operating officer—both former executives at Houston-based Cheniere Energy.

The C-suite moves come three months after Joulent raised $1.75 billion from National Grid Ventures.

Michael Wortley joins Joulent as co-president and CFO. Wortley most recently was executive vice president and CFO at Cheniere, an LNG producer and exporter.

In conjunction with Wortley’s hiring, Brian Boland, who was Joulent’s interim CFO, has been named executive vice president, chief investment officer, and head of strategy.

Corey Grindal comes to Joulent as co-president and COO. Grindal most recently was executive vice president and COO at Cheniere.

“As Joulent evolves to meet the growing demand for power infrastructure, our expanded leadership team will help ensure we continue delivering the execution certainty our customers, partners, and investors expect,” Chris James, Joulent’s founder and CEO, said in a press release.

“Corey and Michael are accomplished operators with exceptional records of building and leading world-class energy infrastructure businesses, where they have embedded a culture defined by operational excellence and disciplined execution,” James added.

Joulet builds dedicated power-generating facilities that feed directly into data centers and other power-dependent facilities. This eliminates the need for companies to draw power from grids.

“With an initial multi-gigawatt development portfolio and strategic partnerships across the energy, infrastructure, and data center ecosystem, Joulent is helping remove power constraints to enable the next chapter of American innovation and U.S. reindustrialization,” the company says.

The $1.75 billion minority investment from National Grid Ventures complements Joulent’s existing partnerships.

Joulent, founded in 2023, emerged from stealth mode this summer. The company was founded by investment firm Engine No. 1.

Joulent’s first project, the Project Kilby natural gas facility in West Texas, will be co-located with a Microsoft data center. It’ll deliver about 2.67 gigawatts of power under a 20-year deal between Microsoft and Energy Forge One, a 50/50 joint venture between Chevron and Joulent.
Al Vickers, XGS Energy's new COO, and Richard Chong, the company's new CFO. Photos courtesy XGS/LinkedIn

Houston geothermal startup adds former BP, Calpine execs to C-suite

new leaders

XGS Energy, a Houston-based developer of geothermal power systems, has added several energy industry veterans to its C-suite this summer.

The company named Al Vickers as its new chief operating officer earlier this month. Vickers will replace Ghazal Izadi in the role, as she moves into the chief growth officer position.

Vickers previously served as CEO of BP's U.S. Low Carbon Energy business and most recently was COO of Houston-based Grid United, which develops next-generation transmission infrastructure.

“I have spent my career developing, building, and operating large, complex energy infrastructure, and I am excited to work with XGS’s proven technology, which is ready to deliver clean, round-the-clock power at the scale the grid and customers need,” Vickers said in a news release. “XGS sits at the intersection of innovation, affordability, demand growth, responsible infrastructure development, and long-term energy resilience. I’m excited to roll up my sleeves and apply best practices from both oil and gas and infrastructure development to deliver gigawatt-scale geothermal projects.”

Kurt Fricker, who most recently held leadership roles at Hess Corporation, was also announced as XGS's new chief procurement officer.

The hires come shortly after XGS announced Richard Chong as its new chief financial officer in May.

Chong joins XGS from Houston-based power producer Calpine, where he most recently was vice president of finance. His work there included leading $2.25 billion in financing for Geysers, the world’s largest geothermal power complex.

Chong says XGS’ proven technology and the rising demand for clean power will help the company execute on its multi-gigawatt pipeline.

“I look forward to applying the experience I’ve built over two decades in energy finance to help XGS deliver clean, reliable power to customers and unlock the massive development opportunity ahead for next-generation geothermal,” Chong said in the release.

XGS’ first project is a 150-megawatt geothermal facility in New Mexico. It will supply around-the-clock electricity to the grid operated by Public Service Co. of New Mexico in support of Meta data centers.

XGS recently tapped Houston-based energy technology company Baker Hughes to provide engineering services for the New Mexico project.

XGS’ geothermal system uses thermally conductive materials to deliver affordable energy anywhere hot rock exists — without the need for water resources or specific geological conditions. This results in lower-risk projects, more site options, easier permitting and faster deployment.

Since 2023, XGS has raised nearly $57 million in venture capital.

XGS launched in 2008 in Palo Alto, California, as Geothermic Solution. In conjunction with its Series A round in 2023, the company rebranded to its current name. The company recently moved its headquarters to Houston, according to the Houston Business Journal.

Longtime Oxy CEO Vicki Hollub will retire June 1. Richard Jackson, the company's current COO, will replace her in the role. Photos via oxy.com

Oxy officially announces CEO transition, names successor

new leader

Houston-based Occidental (Oxy) has officially announced its longtime CEO's retirement and her successor.

Oxy shared last week that Vicki Hollub will retire June 1. Reuters first reported Hollub's plan to retire in March, but a firm date had not been set. Hollub will remain on Oxy's board of directors.

Richard Jackson, who currently serves as Oxy's COO, will replace Hollub in the CEO role.

“It has been a privilege to lead Occidental and work alongside such a talented team for more than 40 years," Hollub shared in a news release. "Following the recently completed decade-long transformation of the company, we now have the best portfolio and the best technical expertise in Occidental’s history. With this strong foundation in place, a clear path forward and a leader like Richard, who has the experience and vision to elevate Occidental, now is the right time for this transition. “I look forward to supporting Richard and the Board through my continued role as a director.”

Hollub has held the top leadership position at Oxy since 2016 and has been with the energy giant for more than 40 years. Before being named CEO, she served as COO and senior executive vice president at the company. She led strategic acquisitions of Anadarko Petroleum in 2019 and CrownRock in 2024, and was the first woman selected to lead a major U.S. oil and gas company.

Hollub also played a key role in leading Oxy's future as a "carbon management company."

Jackson has been with Oxy since 2003. He has held numerous leadership positions, including president of U.S. onshore oil and gas, president of low carbon integrated technologies, general manager of the Permian Delaware Basin and enhanced oil recovery oil and gas, vice president of investor relations, and vice president of drilling Americas.

He was instrumental in launching Oxy Low Carbon Ventures, which focuses DAC, carbon sequestration and low-carbon fuels through businesses like 1PointFive, TerraLithium and others, according to the company. He also serves on the Oil and Gas Climate Initiative’s Climate Investment Board and the American Petroleum Institute’s Upstream Committee. He holds a bachelor's degree in petroleum engineering from Texas A&M University.

Jackson was named COO of Oxy in October 2025. In his new role as CEO, he will also join the board of directors, effective June 1.

“I am grateful to be appointed President and CEO of Occidental and excited about the opportunity to execute from the strong position and capabilities that we built under Vicki’s leadership,” Jackson added in the release. “It means a lot to me personally to be a part of our Occidental team. I am committed to delivering value from our significant and high-quality resource base. We have a tremendous opportunity to focus on organic improvement and execution to deliver meaningful value for our employees, shareholders and partners.”

Lawson Gow and Kelsey Kearns have stepped into new leadership roles at Greentown Labs. Photos courtesy Greentown/LinkedIn

Greentown Labs names new COO, appoints new Head of Houston

new leaders

Greentown Labs has reshuffled its leadership, elevating Houston leaders into new roles.

Lawson Gow was named COO of the Houston- and Boston-based climatech incubator in February 2026. In his new role, he will focus on optimizing Greentown's structure, building new internal and external systems and developing a plan for growth.

Gow was named Head of Houston in July. He previously founded The Cannon, a coworking space with eight locations in the Houston area, with additional partner spaces. He also recently served as managing partner at Houston-based investment and advisory firm Helium Capital. Gow is the son of David Gow, founder of Energy Capital's parent company, Gow Media.

Kelsey Kearns, who previously served as Director of Community Strategy at Greentown, was named as Gow's replacement in the Houston-focused role. As the new Head of Houston, she will lead daily operations, work to connect the city's climate and innovation ecosystem and founders, strengthen partnerships and accelerate solutions.

"I'm honored and grateful to step into this new role," Kearns said in an email. "My goal is for Greentown to thrive so our founders can thrive! That means supporting their connection to the capital, pilots, and customers they need to grow while building partnerships across Houston's innovation ecosystem. I want Greentown Houston to become the playbook for every future Greentown expansion."

Before joining Greentown Houston, Kearns served as director of business development at Howdy.com, an Austin-based technology staffing company.

"Kelsey is such a perfect fit to lead Greentown Houston," Gow added in an email. "She's deeply passionate about the entrepreneurial community here and has worked throughout and across the ecosystem for years. She's built an awesome dream team here and has helped reinvigorate Greentown's presence and role in Houston's innovation economy."

Earlier this year, Greentown also named Julia Travaglini as the Head of its Boston incubator. Travaglini has held multiple leadership roles at Greentown since 2016. The organization named Georgina Campbell Flatter as its new CEO in early 2025.

Promethean Energy has named Martyn Fear as its new COO. Photo courtesy Promethean Energy.

Houston energy co. names new COO to scale offshore decommissioning

new hire

Houston-based Promethean Energy has named a new COO as it looks to scale.

Martyn Fear, former CEO of Altamesa Energy Canada Inc., will assume the role, the company announced last week. He brings decades of experience at energy companies such as BP and Maersk Oil and has held board positions at several private equity and venture-backed firms.

“Promethean has built a differentiated platform for managing and retiring late-life assets safely, efficiently, and responsibly,” Fear said in a news release. “The industry is facing a structural shift as decommissioning moves to the forefront, and the opportunity to combine operational excellence, disciplined project delivery, and innovative commercial models is incredibly compelling."

Promethean has developed an environmentally sustainable, integrated model for late-life asset management and offshore well decommissioning. Fear will oversee day-to-day operations at Promethean and the execution of this integrated operator-service model as the company looks to scale and expand to new markets.

“Martyn is a proven leader with a deep operational track record and a passion for building high-performance, safety-first organizations,” Aditya Singh, Promethean's CEO, added in the release. “As Promethean enters its next phase—scaling our integrated operator-service model and delivering first-time-right decommissioning at pace—his experience in transforming complex asset portfolios and leading global teams makes him the ideal COO to drive operational execution while we continue to advance our strategic vision.”

Last May, the company successfully decommissioned offshore orphaned wells in the Matagorda Island lease area. In November, it also announced that it had completed a multi-client project to safely plug and abandon an orphaned well on a storm-damaged platform in the South Timbalier lease area.

Both projects were based in the Gulf of Mexico, where Promethean is looking to grow.

John Carrington is now CEO of Enchanted Rock. Photo courtesy Enchanted Rock.

Houston microgrid company names new CEO

new hire

Houston-based electric microgrid company Enchanted Rock has named a new CEO.

John Carrington has assumed the role after serving as Enchanted Rock's executive chairman since June, the company announced earlier this month.

Carrington most recently was CEO of Houston-based Stem, which offers AI-enabled software and services designed for setting up and operating clean energy facilities. He stepped down as Stem’s CEO in September 2024. Stem, which was founded in 2006 and went public under Carrington's leadership in 2021, was previously based in San Francisco.

Carrington has also held senior leadership roles at Miasolé, First Solar and GE.

Corey Amthor has served as acting CEO of Enchanted Rock since June. He succeeded Enchanted Rock founder Thomas McAndrew in the role, with McAndrew staying on with the company as a strategic advisor and board member. With the hiring of Carrington, Amthor has returned to his role as president. According to the company, Amthor and Carrington will "partner to drive the company’s next phase of growth."

“I’m proud to join a leadership team known for technical excellence and execution, and with our company-wide commitment to innovation, we are well positioned to navigate this moment of unprecedented demand and advance our mission alongside our customers nationwide,” Carrington said in the news release. “Enchanted Rock’s technology platform delivers resilient, clean and scalable ultra-low-emissions onsite power that solves some of the most urgent challenges facing our country today. I’m energized by the strong momentum and growing market demand for our solutions, and we remain committed to providing data centers and other critical sectors with the reliable power essential to their operations.”

This summer, Enchanted Rock also announced that Ian Blakely would reassume the role of CFO at the company. He previously served as chief strategy officer. Paul Froutan, Enchanted Rock's former CTO, was also named COO last year.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

TotalEnergies expands solar joint venture with $1.2B portfolio in Texas, Ohio

solar expansion

TotalEnergies, a French company whose U.S. headquarters is in Houston, announced this month that it is expanding its renewable energy joint venture with New York-based investment firm KKR by adding 700 megawatts of utility-scale solar projects.

The deal will add three utility-scale solar assets in Texas and Ohio, which are expected to reach commercial operation by Q1 2027, according to a news release from the company. The portfolio is valued at $1.2 billion.

The 50/50 joint venture between TotalEnergies and KKR currently holds 1.4 gigawatts of renewable energy and will grow to 2.1 gigawatts.

The new deal is expected to close this year. Once completed, TotalEnergies will operate the assets. The electricity generated from the solar projects will be sold to third parties, the company reports.

The companies originally formed the joint venture about a year ago when TotalEnergies sold KKR a 50 percent stake in a North American solar portfolio valued at $1.25 billion. The deal originally included six utility-scale solar assets, primarily located in the U.S.

“TotalEnergies is a renewable energy industry leader globally, and we are thrilled to establish this joint venture with the TotalEnergies team to support their renewables business," Cecilio Velasco, managing director KKR, said in a release last year. “We have long been investors in renewables through our infrastructure platform, having committed more than $23 billion to date in energy transition investments. TotalEnergies’ North American solar portfolio is a great fit for us, representing high-quality renewable energy assets with long term contracts.”

TotalEnergies reports that by June 2026 it held more than 37 gigawatts of gross renewable power generation capacity. It aims to achieve over 100 terawatt-hours of net electricity production by 2030.

The company signed a major power purchase agreement with Google earlier this year. Through the deal, TotalEnergies will supply the tech giant with 1 gigawatt of solar power for its data centers in Texas over a 15-year span.

However, the company also recently redirected nearly $1 billion in capital away from wind energy projects and "decided to renounce offshore wind development in the United States." Read more here.

Houston researchers develop compact carbon capture tech for data centers

AI emissions

Two scientists from the University of Houston have been experimenting with new carbon capture systems that fit inside a standard shipping container, which have the potential to make eliminating carbon output from industrial sites much easier.

The capture of industrial carbon is an important complement to the fight against climate change, as well as winning tax credits for businesses that use carbon capture technology.

The problem is that such systems are often measured in acres, making them expensive to build and extremely power-hungry to actually use. UH Engineering Professor Mim Rahimi and former UH Ph.D. student Ahmad Hassan (now a postdoctoral associate at Harvard) have managed to fit their new system, the Small Modular Electrochemical Container (SMECs), inside a standard 40-foot shipping crate, making them compact and modular enough to be installed almost anywhere for operations of all sizes. Their research was recently published in the journal Environmental Science & Technology.

“With a conventional system, you’re building a 130-foot-tall structure designed for a specific power plant. With our technology, we can adjust the capacity by simply turning containers on or off,” Rahimi said in a news release. “That flexibility is particularly important for data centers, where electricity can come from a combination of natural gas and renewable sources.”

Rahimi and Hassan used simulated gas models to show that under optimal conditions, the SMEC used electrochemically mediated amine regeneration (EMAR) cells developed in Rahimi’s lab to capture 90 percent of carbon under optimal conditions through 300 cycles over 50 hours.

Encouraged, the team then modeled a 360-megawatt natural gas power plant associated with OpenAI’s Stargate AI data center project in Abilene, Texas. In addition to the savings on infrastructure costs, 20 of the researchers’ shipping container systems were able to capture 98 percent of carbon from Stargate’s 875-acre campus based on the model.

The looming energy costs and subsequent carbon emissions from data centers are a real concern. Estimates from the U.S. Department of Energy hypothesize that 12 percent of America’s energy needs could be gobbled up by the centers as soon as 2028. That is a massive new source of carbon. The flexibility of the SMEC means they can be deployed wherever the centers spring up.

“We’re taking a technology that traditionally requires enormous infrastructure and finding a way to fit it inside a shipping container,” Rahimi added in the release. “That opens up entirely new possibilities for how and where carbon capture systems can be used.”

In the future, the researchers say they plan to look at ways to adapt the technology to capture carbon dioxide directly from the atmosphere.

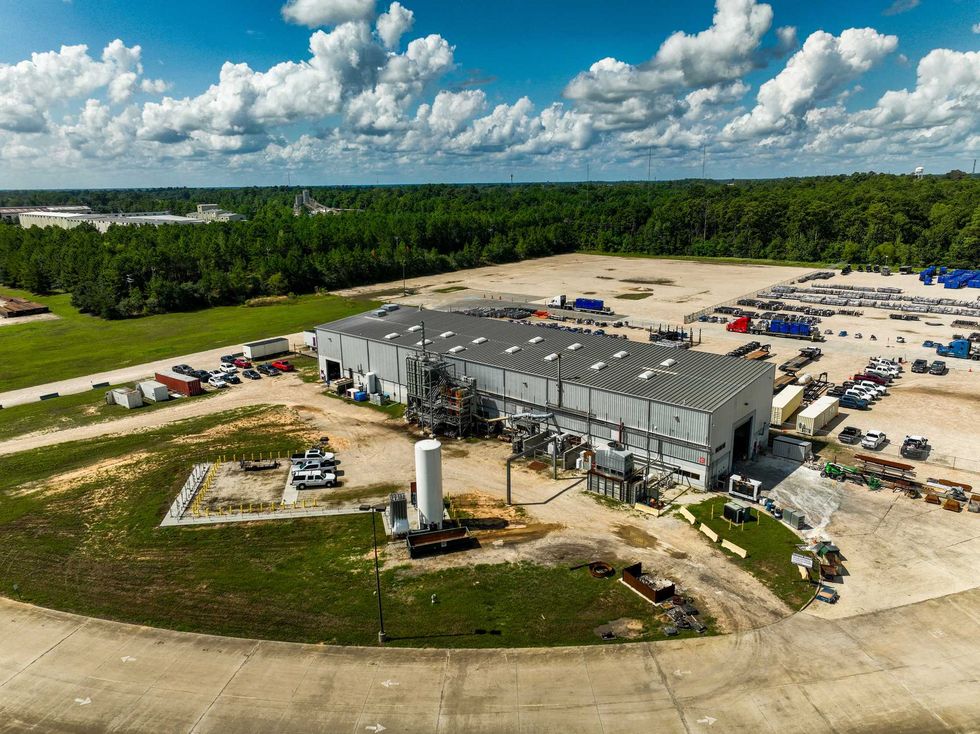
Hertha Metals breaks ground on $100M high-purity iron factory in Conroe

coming soon

Shortly after announcing a $133.65 Series A funding round, Conroe-based Hertha Metals broke ground Oct. 8 on a $100 million factory that will produce steel-grade and magnet-grade high-purity iron.

Hertha’s Chalyx plant, located in Conroe, will manufacture a total of about 10,000 metric tons per year of magnet-grade and steel-grade high-purity iron. The factory will use Hertha’s single-step process to generate high-purity iron for rare-earth-magnet and steel manufacturers in the U.S.

Hertha says Chalyx will be the first U.S. commercial plant for production of magnet-grade high-purity iron.

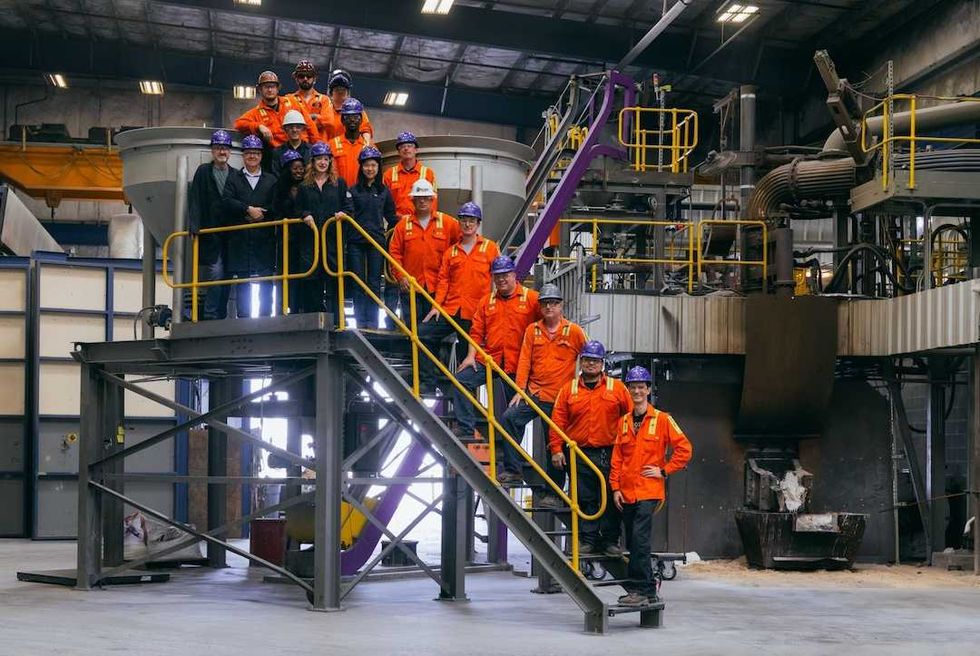
Chalyx is being built next to Hertha’s headquarters and its Pi100 pilot plant, which will remain in operation. Chalyx and Pi100 will form the first modern-day iron and steel “innovation complex” in the U.S., the company says.

“I founded Hertha Metals because I believed we could significantly improve how the world makes iron and steel from ore, and that an industry so fundamental to our future still had enormous room for invention,” Laureen Meroueh, founder and CEO of Hertha, said in a press release.

The 4-year-old startup says the Chalyx complex will lay the foundation for its first 500,000-ton-per-year steel mill.

Chalyx’s first priority is making high-purity iron for U.S. manufacturers of rare-earth magnets, Hertha says. These magnets are critical components for electric vehicles, data centers, wind turbines and defense systems.

China produces an estimated 94 percent of high-purity iron for rare-earth magnets, according to Hertha.

Aside from iron for rare-earth magnets, Chalyx will make iron and steel for pilot projects in the steel industry.

The plant is expected to come online in late 2027, with production of magnet-grade high-purity iron starting in early 2028.

Today, Hertha employs 32 people, the company says. Once it’s fully operating, the Chalyx plant will employ about 50 people.

Just ahead of the groundbreaking, Hertha announced the $133.65 million Series A round, co-led by Khosla Ventures and Doerr Capital. The round included a $65 million equity investment from the Pentagon.

“Iron and steel have shaped human progress for thousands of years. And I believe there is still an enormous amount left to invent,” Meroueh said at the groundbreaking ceremony.