The politicians point to a recent Texas merger. Photo via Getty Images

Senate Majority Leader Chuck Schumer and 22 other Democratic senators are calling on the Department of Justice to “use every tool” at its disposal to prevent and prosecute alleged collusion and price-fixing in the oil industry.

In a letter Thursday to Attorney General Merrick Garland and other officials, the Democrats said a recent Federal Trade Commission investigation into a high-profile merger uncovered evidence of price-fixing by oil executives that led to higher energy costs for American families and businesses.

The FTC said earlier this month that Scott Sheffield, the former CEO of Texas-based Pioneer Natural Resources, colluded with OPEC and OPEC+ to potentially raise crude oil prices. Sheffield retired from the company in 2016 but returned as CEO in 2019. After retiring again in 2023, he continued to serve on its board.

The FTC cleared Houston-based ExxonMobil's $60 billion deal to buy Pioneer on May 2 but barred Sheffield from joining the new company’s board of directors. Pioneer, which is based in Dallas, said it disagreed with the allegations but would not impede closing of the merger, which was announced in 2023.

In a report, the FTC said collusion by Pioneer and others may have cost the average American household up to $500 per car in increased annual fuel costs, an amount Democrats called “an unwelcome tax that is particularly burdensome for lower-income families.'' Meanwhile, Exxon Mobil and other major oil companies collectively earned more than $300 billion in profits over the last two years, "a surge that many market experts believe cannot be explained away by increased production costs from the (coronavirus) pandemic or inflation,” Democrats said.

The letter calls for the Justice Department to launch an industry-wide investigation into possible violations of the Sherman Antitrust Act. It outlined how “Big Oil’s alleged collusion with OPEC is a national security concern that aids countries looking to undermine the U.S.," including Russia and Iran.

“Corporate malfeasance must be confronted, or it will proliferate," the letter said. “These alleged offenses do not simply enrich corporations; hardworking Americans end up paying the price through higher costs for gas, fuel and related consumer products. The DOJ must protect consumers, small businesses and the public from petroleum-market collusion."

The letter by Senate Democrats was the latest in a series of partisan actions targeting the oil industry.

Separately, Democratic Sen. Sheldon Whitehouse of Rhode Island and Democratic Rep. Jamie Raskin of Maryland have formally asked the Justice Department to investigate whether Exxon, Chevron and other oil companies misled the public over decades about the climate effects of burning fossil fuels. Whitehouse and Raskin led a multiyear investigation that uncovered what they described as “damning new documents that exposed the fossil fuel industry’s ongoing efforts to deceive the public and block climate action.”

Republicans, meanwhile, have attacked President Joe Biden's energy policies, including a freeze on liquefied natural gas exports, restrictions on new oil and gas leasing on a petroleum reserve in Alaska and a decision to charge companies higher rates to drill for oil and natural gas on federal lands.

Sen. John Barrasso, the top Republican on the Senate Energy Committee, said the Democratic president was “doing all he can to make it economically impossible to produce energy on federal lands.''

The letter released Thursday was signed by 23 Democrats, including Schumer, Whitehouse, Senate Commerce Committee Chairwoman Maria Cantwell of Washington state and Senate Judiciary Committee Chairman Dick Durbin of Illinois.
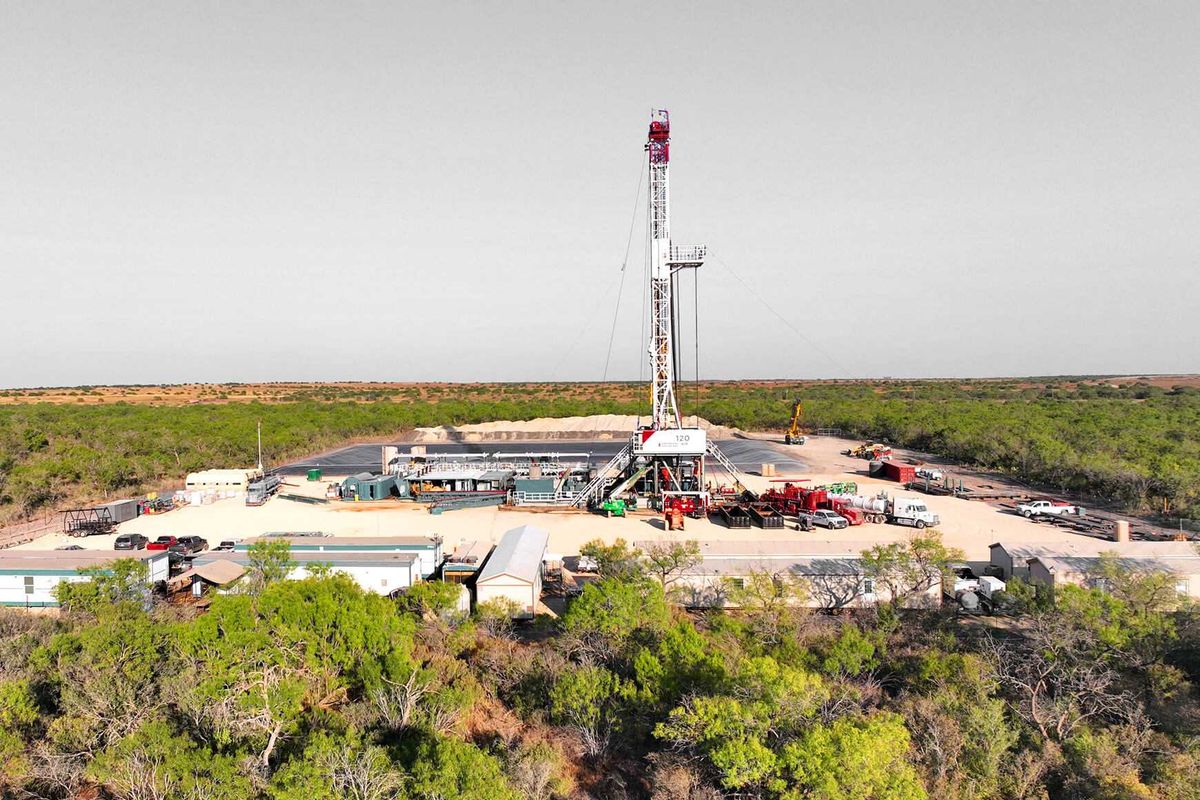
ExxonMobil got initial approval of its $60 billion deal to buy Houston-based Pioneer Natural Resources. Photo via ExxonMobil.com

ExxonMobil's $60B acquisition gets FTC clearance — with one condition

M&A moves

ExxonMobil's $60 billion deal to buy Pioneer Natural Resources on Thursday received clearance from the Federal Trade Commission, but the former CEO of Pioneer was barred from joining the new company's board of directors.

The FTC said Thursday that Scott Sheffield, who founded Pioneer in 1997, colluded with OPEC and OPEC+ to potentially raise crude oil prices. Sheffield retired from the company in 2016, but he returned as president and CEO in 2019, served as CEO from 2021 to 2023, and continues to serve on the board. Since Jan. 1, he has served as special adviser to the company’s chief executive.

“Through public statements, text messages, in-person meetings, WhatsApp conversations and other communications while at Pioneer, Sheffield sought to align oil production across the Permian Basin in West Texas and New Mexico with OPEC+,” according to the FTC. It proposed a consent order that Exxon won't appoint any Pioneer employee, with a few exceptions, to its board.

Dallas-based Pioneer said in a statement it disagreed with the allegations but would not impede closing of the merger, which was announced in October 2023.

“Sheffield and Pioneer believe that the FTC’s complaint reflects a fundamental misunderstanding of the U.S. and global oil markets and misreads the nature and intent of Mr. Sheffield’s actions,” the company said.

Senate Majority Leader Chuck Schumer, D-N.Y., said it was “disappointing that FTC is making the same mistake they made 25 years ago when I warned about the Exxon and Mobil merger in 1999.”

Schumer and 22 other Democratic senators had urged the FTC to investigate the deal and a separate merger between Chevron and Hess, saying they could lead to higher prices, hurt competition and force families to pay more at the pump.

The deal with Pioneer vastly expands Exxon’s presence in the Permian Basin, a huge oilfield that straddles the border between Texas and New Mexico. Pioneer’s more than 850,000 net acres in the Midland Basin will be combined with Exxon’s 570,000 net acres in the Delaware and Midland Basin, nearly contiguous fields that will allow the combined company to trim costs.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Rice University spinouts named among 50 top cleantech companies to watch

green team

Two Rice University spinouts, Coflux Purification and DexMat, appear on a new list of the world’s 50 cleantech companies to watch.

Cleantech Group’s 2026 Cleantech 50 to Watch list recognizes early-stage companies “creating groundbreaking solutions to address some of the world’s most pressing environmental and sustainability challenges.”

Cleantech Group, a market research, consulting, and events company, selects the 50 honorees based on insights from analysts and early-stage innovators, along with public nominations.

Destroying “forever chemicals”

Coflux, founded in 2024, offers an onsite treatment system that captures and destroys manufactured “forever chemicals”—per- and polyfluoroalkyl substances—in water and wastewater. It’s a member of Greentown Houston.

Alec Ajnsztajn, CEO; Jeremy Daum, chief technology officer; and Dana Vazquez, chief commercial officer, co-founded Coflux. Ajnsztajn and Daum earned doctoral degrees from Rice, and Vazquez earned an MBA from the university.

Coflux spun out of Rice labs directed by professors Rafael Verduzco and Pulickel Ajayan.

Last year, Coflux received a $175,000 grant from the U.S. Food and Drug Administration’s National Institute of Food and Agriculture. The startup has also raised more than $500,000 in non-dilutive funding, including $80,000 awarded in 2024 by Rice’s One Small Step Grant program.

Promoting an alternative to copper

DexMat, founded in 2015, produces carbon nanotube products such as fibers, yarns, cables, and fabric. The company’s products address demand for materials that can reduce carbon emissions, according to CB Insights.

Its main product, Galvorn, is a copper alternative made of carbon nanotube fibers. CB Insights says Galvorn is engineered to be lighter and stronger than traditional conductive materials like carbon and steel. It’s used in industries such as energy, aerospace, defense, automotive, consumer electronics, and health care.

DexMat emerged from Matteo Pasquali’s Carbon Lab at Rice. Pasquali, co-founder of DexMat, co-invented the company’s technology with the late Nobel Prize-winning chemist Rick Smalley. Smalley was a professor of chemistry, physics, and astronomy at Rice.

Pasquali is a professor of chemical and biomolecular engineering, chemistry, materials science, and nanoengineering at Rice. He co-founded DexMat with Rice graduate Dmitri Tsentalovich, the company’s director of product innovation.

Earlier this year, DexMat raised $5 million in seed funding from Non Sibi Ventures, Governance Partners, Tailwind Futures, BetterWay, Capital Factory, and other investors. The company also secured $3 million in non-dilutive funding.

In 2023, DexMat raised $3 million in a pre-seed round led by Shell Ventures.

TotalEnergies expands solar joint venture with $1.2B portfolio in Texas, Ohio

solar expansion

TotalEnergies, a French company whose U.S. headquarters is in Houston, announced this month that it is expanding its renewable energy joint venture with New York-based investment firm KKR by adding 700 megawatts of utility-scale solar projects.

The deal will add three utility-scale solar assets in Texas and Ohio, which are expected to reach commercial operation by Q1 2027, according to a news release from the company. The portfolio is valued at $1.2 billion.

The 50/50 joint venture between TotalEnergies and KKR currently holds 1.4 gigawatts of renewable energy and will grow to 2.1 gigawatts.

The new deal is expected to close this year. Once completed, TotalEnergies will operate the assets. The electricity generated from the solar projects will be sold to third parties, the company reports.

The companies originally formed the joint venture about a year ago when TotalEnergies sold KKR a 50 percent stake in a North American solar portfolio valued at $1.25 billion. The deal originally included six utility-scale solar assets, primarily located in the U.S.

“TotalEnergies is a renewable energy industry leader globally, and we are thrilled to establish this joint venture with the TotalEnergies team to support their renewables business," Cecilio Velasco, managing director KKR, said in a release last year. “We have long been investors in renewables through our infrastructure platform, having committed more than $23 billion to date in energy transition investments. TotalEnergies’ North American solar portfolio is a great fit for us, representing high-quality renewable energy assets with long term contracts.”

TotalEnergies reports that by June 2026 it held more than 37 gigawatts of gross renewable power generation capacity. It aims to achieve over 100 terawatt-hours of net electricity production by 2030.

The company signed a major power purchase agreement with Google earlier this year. Through the deal, TotalEnergies will supply the tech giant with 1 gigawatt of solar power for its data centers in Texas over a 15-year span.

However, the company also recently redirected nearly $1 billion in capital away from wind energy projects and "decided to renounce offshore wind development in the United States." Read more here.