The study provides the first large-scale statistical analysis of data center location strategies in the U.S. Photo courtesy Rice University.

Recent power outages and the surge in AI-driven computing have made data center siting decisions more consequential than ever, especially as energy and water constraints tighten. Communities invest public dollars on the promise of jobs and growth, while firms weigh long-term commitments to land, power and connectivity.

Against that evolving backdrop, a critical question comes into focus: Where do data centers get built — and what actually drives those decisions?

A new study by Tommy Pan Fang (Rice Business) and Shane Greenstein (Harvard Business School) provides the first large-scale statistical analysis of data center location strategies across the United States. It offers policymakers and firms a clearer starting point for understanding how different types of data centers respond to economic and strategic incentives.

Published in the journal Strategy Science, the study examines two major types of infrastructure: third-party colocation centers that lease server space to multiple firms, and hyperscale cloud centers owned by providers like Amazon, Google and Microsoft.

Key takeaways:

  • Third-party colocation centers are physical facilities in close proximity to firms that use them, while cloud providers operate large data centers from a distance and sell access to virtualized computing resources as on‑demand services over the internet.
  • Hospitals and financial firms often require urban third-party centers for low latency and regulatory compliance, while batch processing and many AI workloads can operate more efficiently from lower-cost cloud hubs.
  • For policymakers trying to attract data centers, access to reliable power, water and high-capacity internet matter more than tax incentives.

What are the two main data center location strategies?

The study draws on pre-pandemic data from 2018 and 2019, a period of relative geographic stability in supply and demand. This window gives researchers a clean baseline before remote work, AI demand and new infrastructure pressures began reshaping internet traffic patterns.

The findings show that data centers follow a bifurcated geography:

  • Third-party centers cluster in dense urban markets, where buyers prioritize proximity to customers despite higher land and operating costs.
  • Cloud providers, by contrast, concentrate massive sites in a small number of lower-density regions, where electricity, land and construction are cheaper and economies of scale are easier to achieve.

Third-party data centers, in other words, follow demand. They locate in urban markets where firms in finance, healthcare and IT value low latency, secure storage, and compliance with regulatory standards.

Using county-level data, the researchers modeled how population density, industry mix and operating costs predict where new centers enter. Every U.S. metro with more than 700,000 residents had at least one third-party provider, while many mid-sized cities had none.
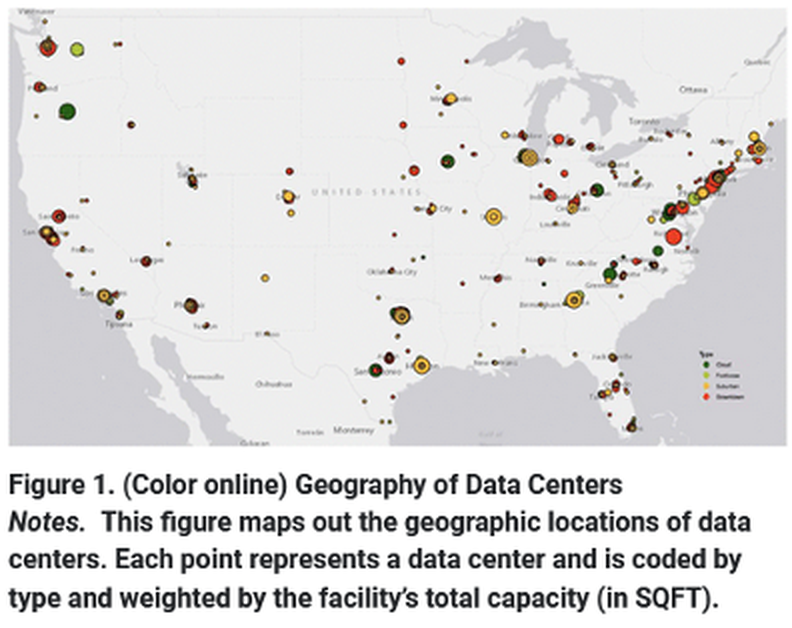
Map of data centers

This pattern challenges common assumptions. Third-party facilities are more distributed across urban America than prevailing narratives suggest.

“For industries where speed is everything, being too far from the physical infrastructure can meaningfully affect performance and risk,” Pan Fang says. “Proximity isn’t optional for sectors that can’t absorb delay.”

In critical operations, even slight pauses can have real consequences. For hospital systems, lag can affect performance and risk exposure. And in high-frequency trading, milliseconds can determine whether value is captured or lost in a transaction.

Why does distance matter for cloud data center costs?

For cloud providers, the picture looks very different. Their decisions follow a logic shaped primarily by cost and scale. Because cloud services can be delivered from afar, firms tend to build enormous sites in low-density regions where power is cheap and land is abundant.

These facilities can draw hundreds of megawatts of electricity and operate with far fewer employees than urban centers. “The cloud can serve almost anywhere,” Pan Fang says, “so location is a question of cost before geography.”

The study finds that cloud infrastructure clusters around network backbones and energy economics, not talent pools. Well-known hubs like Ashburn, Virginia — often called “Data Center Alley” — reflect this logic, having benefited from early network infrastructure that made them natural convergence points for digital traffic.

Local governments often try to lure data centers with tax incentives, betting they will create high-tech jobs. But the study suggests other factors matter more to cloud providers, including construction costs, network connectivity and access to reliable, affordable electricity.

When cloud centers need a local presence, distance can sometimes become a constraint. Providers often address this by working alongside third-party operators. “Third-party centers can complement cloud firms when they need a foothold closer to customers,” Pan Fang says.

That hybrid pattern — massive regional hubs complementing strategic colocation — may define the next phase of data center growth.

Looking ahead, shifts in remote work, climate resilience, energy prices and AI-driven computing may reshape where new facilities go. Some workloads may move closer to users, while others may consolidate into large rural hubs. Emerging data-sovereignty rules could also redirect investment beyond the United States.

“The cloud feels weightless,” Pan Fang says, “but it rests on real choices about land, power and proximity.”

---

This article originally appeared on Rice Business Wisdom. Written by Scott Pett. Pan Fang and Greenstein (2025). “Where the Cloud Rests: The Economic Geography of Data Centers,” Strategy Science.

Ad Placement 300x100
Ad Placement 300x600

CultureMap Emails are Awesome

Houston’s Fervo Energy amasses $12B backlog of orders

q3 results

Houston-based geothermal power company Fervo Energy saw a 65 percent spike in purchase orders during the third quarter.

During Fervo’s third-quarter earnings call, Tim Latimer, co-founder, chair, president and CEO, said the company had a $11.9 billion backlog of orders, up from $7.2 billion in the previous quarter.

Those numbers didn’t translate to robust financial results in the third quarter, though. It closed the quarter with an operating loss of $43 million on revenue of just $116,000.

Beyond the billions of dollars in signed purchase agreements, Fervo is in talks with prospective customers in the utility, industrial data-center sectors, Latimer said. About half the potential customers are in the data-center sector, 35 percent in the utility sector and 15 percent in the industrial sector.

Latimer said the broad-based demand reflected by the backlog and the discussions with potential customers reinforces the critical need for reliable, readily available power.

“Our approach to power delivery will continue to blend front-of-the-meter and behind-the-meter development,” he said. “Grid-connected assets remain the foundation, though behind-the-meter gives customers a faster path to power when transmission time lines lag their need.”

Front-of-the-meter refers to power plants, utility-scale solar and wind farms, large grid batteries, and transmission and distribution infrastructure. Behind-the-meter assets sit on the customer side of the meter, such as backup generators and EV chargers at homes, businesses, factories and other everyday places.

The order backlog isn’t Fervo’s only recent milestone. In late September, the company’s Cape Station geothermal plant in Utah started delivering its first utility-scale geothermal power to the grid. The plant is producing about 33 megawatts of power.

Earlier in September, Fervo signed a 15-year deal to supply about 396 megawatts of power for Google data centers. The power will be delivered in four 99-megawatt batches. The company filed its $1.89 billion IPO this spring.

3 Houston incubators supporting hard tech, energy transition, and beyond

Meet The Finalists

It takes a village to launch a business. That's where Houston's network of incubators and accelerators can step in, providing the resources, mentorship and community needed to push a fledgling company forward.

As part of InnovationMap's 2026 Houston Innovation Awards, the Incubator/Accelerator of the Year category honors a local organization that is championing and fueling the growth of Houston startups.

Three incubators and accelerators have been named finalists for the 2026 award. They support startups ranging from hard tech companies to food and youth concepts.

Read more about these organizations below. The 2026 winners will be announced on InnovationMap.com in mid-November.

Activate

Hard tech incubator Activate supports scientists in "the outset of their entrepreneurial journey." The Houston hub was introduced in 2024, and joins others in Boston, New York, and Berkley, California—where Activate is headquartered. It named its third Houston cohort this summer.

The two-year program graduated its first class of Houston fellows in 2026 and saw its first alumni IPO from Houston-based Fervo Energy, which previously participated in a Berkley cohort. Nationally, it has supported 346 fellows and 276 companies since 2015. Those companies have raised more than $6 billion in follow-on funding, according to Activate. In Houston, it has supported Houston startups like energy transition leaders Solidec and FlowCellutions. Activate Houston is led by managing director Jeremy Pitts, who co-founded Greentown Labs in Boston. It is based out of the Ion.

Impact Hub Houston

Impact Hub Houston supports early-stage ventures at various stages of development through innovative programs that address pressing societal issues. The nonprofit organization supports social impact startups through mentorship, connections and training opportunities.

There are more than 110 Impact Hubs globally with members spanning 72 countries. Launched in 2018, Impact Hub Houston says its membership tripled by the beginning of 2026. This year brought major milestones for the community, including the launch of its Ideas to Impact Accelerator, which supported 11 founders across the health, education, food systems, civic technology and workforce development sectors. It also received funding from more than 20 international Impact Hubs to develop SYNC, a collaboration platform that 25 Impact Hubs across five continents have committed to pilot. The organization has worked with local startups including Myoviva Health, The Change Lab and INNERVERSE Inc.

MarMo Innovation

Galveston-based business incubator MarMo Innovation is focused on removing barriers to entrepreneurship. It aims to provide affordable space, education, mentorship, market access, connections and real-world opportunities that help entrepreneurs move from idea to launch to sustainable growth. The "industry-agnostic" incubator was founded in 2022 and is led by Executive Director Erica Delgadillo.

This year, the organization moved from primarily serving as a coworking and community space into a more comprehensive entrepreneurial incubator by expanding its MarMo Market, MarMo Market Jr. and Lunch LineUp programs. A major focus for MarMo is food entrepreneurship. It is developing an Incubator Kitchen, which MarMo says will support programs like its Cottage to Commercial Bootcamp and Food Biz 101. The organization also expanded its board this year and says it is diversifying its revenue through memberships, events, markets, equipment and space rentals, sponsorships, grants and new entrepreneurial programming.

---

This article first appeared on InnovationMap.com.

Sage Geosystems taps Halliburton to advance Nevada geothermal project

power partnership

Houston-based Sage Geosystems has selected oil and gas powerhouse Halliburton to provide cementing and stimulation services at its enhanced geothermal project in Nevada known as Project Vector.

“Our technology and experience will support Sage as it advances its geopressured geothermal technology,” Shawn Skobel, vice president at Halliburton, said in a news release.

Halliburton will provide Sage with technical modeling, engineering design, and field execution support as part of its specialized cementing and stimulation services at Project Vector at Ormat Technologies' Blue Mountain geothermal power plant. Sage announced the location of the geothermal project in September.

At the time, Sage said it expected to begin drilling the first well at Project Vector this year, with the first electricity to be generated in 2027 and full-scale production to start in 2028.

The project will use Sage’s enhanced geothermal systems (EGS) method in a two-well system to convert geothermal heat into electricity. The project aims to help meet industrial and residential demand, especially as data centers strain energy grids.

Founded in 2020, Sage has raised $159 million across three funding rounds. Its technology aims to reach Earth’s natural heat source deep underground for more consistent power generation and utilizes engineered subsurface reservoirs to minimize water and energy losses and increase net power output. Through the process, Sage says it can enable reliable, 24/7 power generation.

“One of the keys to scaling next-generation geothermal is combining innovative subsurface technology with the proven capabilities and execution of the oil and gas industry,” Jason Peart, Chief Operating Officer of Sage Geosystems, added in the news release. “Halliburton brings decades of experience in well integrity and reservoir stimulation, two critical components of our development approach. By selecting an established industry leader, we are strengthening our ability to execute Project Vector and demonstrate that Sage’s technology can be replicated and deployed commercially across a broad range of geologies.”

Sage is building off prior success of its South Texas SMECI facility, which began operations in August. Project Vector supports Sage’s growing commercial pipeline, which includes a 150-megawatt geothermal power agreement with Meta.